

Lesson 01
What Are Derivatives? Meaning & Types
A plain-language guide to derivative contracts, their common forms, and the risks leverage can add.

Hi, I’m Mr. Chartist.
We will follow one worry of Maya’s, a price three months away, through a forward, a future and an option. By the end you can say what a derivative is, name the four kinds and tell why anyone uses one.
By the end you will be able to answer
- What is a derivative?
- What is a forward?
- What is a future?
What are derivatives? A derivative is a contract whose value comes from something else, such as a share price or an index. The four kinds are forwards, futures, options and swaps. People use them to cancel out a risk, take one on purpose, or trade a price gap. The kinds differ in who has to go through with the deal.
We follow one person, Maya, who runs a burger restaurant. Her story and every price in it are made up for teaching, in Indian rupees, with costs left out.
What is a derivative?
Why someone signs a deal about a price that has not happened yet

My profit arrives in three months. If the shares cost more by then, I lose out. Can I do something today?
Yes. You can agree a price today for a trade that happens later. What you hold is an agreement, not shares.
And the other person? Why would they agree?
They carry the opposite worry, or they take your risk on purpose.
Every kind of derivative answers one question: who has to go through with it?

 ₹1,000 todaythe glass price columnIn 3 months: ?the calendar
Start with a worry. Maya runs a burger restaurant. In three months her quarterly profit will arrive, and she plans to spend it on 100 shares of a company she likes. Today those shares cost ₹1,000 each. In three months they may cost more.
She cannot buy now, because the money is not there yet. She cannot stop the price moving. What she can do is find someone who will agree today on the price for that day. That agreement is a derivative.
What she holds is separate from the shares. Its value follows them. The thing it follows is called the underlying. It can be a share, or an index such as NIFTY 50, which tracks 50 large companies listed on the National Stock Exchange of India (NSE).
A derivative sits beside the thing it follows
Three things to keep separate: the reference, the agreement and your side of it.
- The underlyingNIFTY 50An index level. A number, so nothing to hand over.
- The agreement, written about itQuantity, expiry, priceIts own terms, written about the reference.
- Your side of the agreementBought or soldLong is bought. Short is sold.
There are four kinds: forward, future, option and swap. Maya’s worry takes us through the first three.
What is a forward?
The oldest derivative: two people, one price, one date
A forward is a private deal to buy or sell at a set price on a set day, and both sides must go through with it.
Maya finds a shareholder who is happy to sell in three months. They agree: 100 shares, ₹1,000 each, handed over on that day. They wrote the terms themselves, so the deal is private.
Both sides are bound. On the day, Maya pays ₹1,00,000, whatever the shares cost. If the price is ₹1,100, the shares are worth ₹1,10,000 and she is ₹10,000 ahead. If it is ₹900, she still pays ₹1,00,000 for shares worth ₹90,000. The deal does not care. It fixes her price, and it gives up the chance of a cheaper one.
A forward binds both sides, whatever the price does
Maya agreed ₹1,000 a share for 100 shares. Three possible prices on the day.
Agreed price, every time₹1,00,000
- Delivery-day price ₹900worth ₹90,000Pays ₹10,000 more
- Delivery-day price ₹1,000worth ₹1,00,000Pays the market price
- Delivery-day price ₹1,100worth ₹1,10,000Saves ₹10,000
₹90,000₹1,00,000₹1,10,000
Hypothetical numbers.
A private deal has two weak spots. Each side must trust the other to turn up and pay, and Maya cannot get out without the other person’s agreement. A forward is the seed the future grows from, so it is worth knowing. Whether a private share forward is allowed depends on local law.
What is a future?
Same promise, but anyone can trade it and a clearing house stands in the middle
A future is a forward made standard, so it can trade on an exchange.
The exchange fixes the terms for everyone: what the contract follows, how many units, and the expiry, which is the day the contract ends. Because every contract is identical, any buyer can meet any seller.
Two more things change. A clearing house, the exchange’s settlement arm, stands in the middle of each trade, so each side deals with it and not with a stranger. And gains and losses are settled in cash every day. That is called mark-to-market.
Now the same idea on the index. Maya decides she does not need one company. She wants the market itself, so she looks at a NIFTY 50 future at 25,000. We use 50 units to keep the sums round. The real lot, in November 2026, is 65.
Buying a future is called going long. Selling one is going short. An index cannot be delivered, so the future settles in cash. Say Maya goes long at 25,000. If the price rises 250 points, she gains 250 × 50 = ₹12,500. If it falls 250 points, she loses ₹12,500. The seller has the opposite result.
A future moves point by point, both ways
One NIFTY future bought at 25,000, 50 units. The seller has the mirror result.
NIFTY future rises 250 points from 25,000
NIFTY future falls 250 points from 25,000
Clearing house in the middleEvery rupee one side gains, the other loses, settled in cash each day. 50 units × 250 points.
Hypothetical numbers. Gains and losses are credited and debited every day.
Like the forward, a future binds both sides. Neither can walk away because the price moved the wrong way. Lesson 02 follows one futures contract from order to expiry.
What is an option?
A call is the right to buy. A put is the right to sell
 Premium ₹150the coinStrike 25,000the ticket
An option gives the buyer a right, not a duty. The buyer pays a fee for it, called the premium.
Say Maya, still watching the market, does not like being bound. She wants to gain if it rises, but she does not want to be forced to buy at 25,000 if it falls. An option gives her that choice.
A call option is the right to buy at a fixed price, called the strike. A put option is the right to sell at the strike. The right lasts until the option’s expiry. After that, it is gone.
Because the buyer gets a choice, the buyer pays for it. The seller receives the premium and accepts the duty: if the buyer uses the right, the seller must go through with it.
Maya buys a NIFTY call with a strike of 25,000. The premium is ₹150 per unit, so for 50 units she pays 150 × 50 = ₹7,500. That is the price of the right.
An option is a paid right, with a floor on the cost
One NIFTY call, strike 25,000, premium ₹150 per unit, 50 units.
- Strike, the price you may buy at
- 25,000
- You pay, per unit
- ₹150
The most the buyer can lose is ₹7,500, the premium, before charges. The seller is the one bound if the buyer uses the right.
Hypothetical numbers.
It is also the most the buyer can lose, before charges, because she can let the option expire. The seller’s side is different: lesson 04 covers it. And do not mix up the two prices: the strike is the price she may buy at, and the premium is what the right costs.
How do the four kinds differ?
Forward, future, option and swap side by side
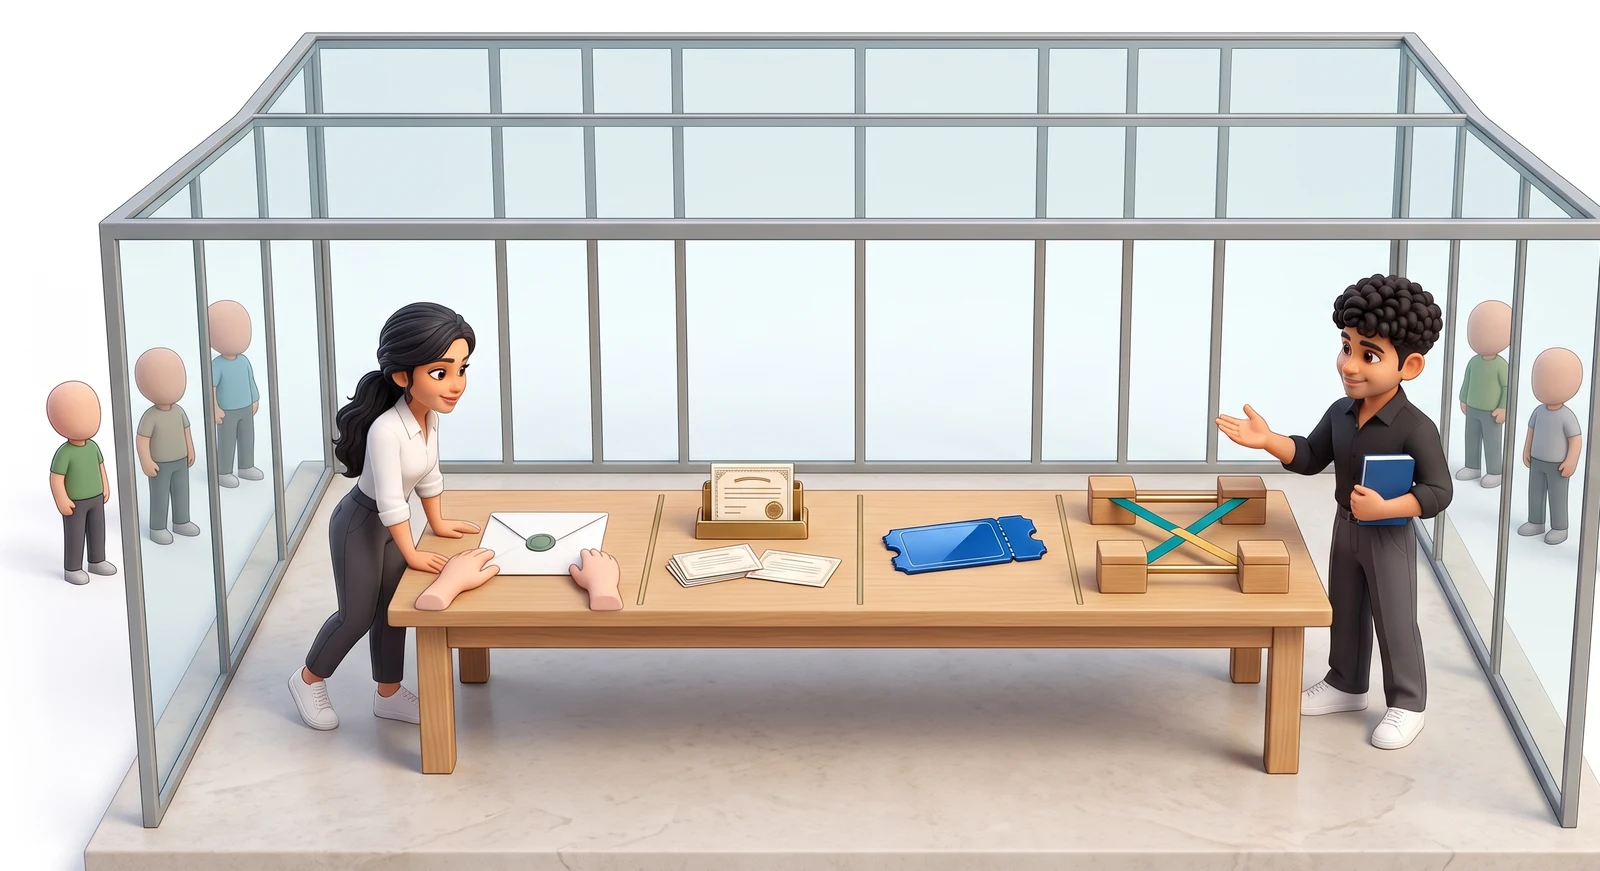 Forwardthe sealed envelopeFuturethe exchange rackOptionthe ticketSwapthe crossed ribbons
They differ by what each side promised. Forward and future bind both sides. An option binds only the seller. A swap trades cash flows.
Put Maya’s three agreements side by side and ask one question: who has to go through with it? In a forward, both sides, privately. In a future, both sides, on an exchange. In an option, only the seller. The buyer chooses.
The four kinds differ by who must go through with it
Where each trades and who has to go through with it.
- ForwardPrivate dealBuyermustSellermustBoth sides must go through with it.
- FutureOn an exchangeBuyermustSellermustBoth sides must go through with it.
- OptionOn an exchangeBuyermaySellermustOnly the seller must. The buyer may choose.
- SwapPrivate, institutionsBuyermustSellermustBoth sides must keep paying their leg.
Solidmust go through with itDashedmay choose
The swap is institutional and is only named in this course.
The fourth kind is the swap. Two sides agree to exchange cash flows over time, for example a fund swapping the return on a basket of shares for a financing payment. Swaps are institutional contracts, not ordinary retail orders, so this course only names them.
The course works with listed futures and options, together called F&O. Lessons 02 and 03 take them one at a time, and lesson 04 looks at the two sides of an option.
How big is the agreement, and what do you actually pay?
Notional exposure, margin and premium
The agreement is far bigger than what you pay. Look again at Maya’s two NIFTY trades: three amounts do three different jobs, and beginners mix them up.
Notional exposure is the size of the position at today’s price, the index level times the units. It is not what you pay.
Margin is money put up as security against an obligation, so the exchange knows daily losses can be paid. We assume 10% of that size. The real figure is set by the exchange and your broker, and it changes. Lesson 37 explains margin.
Premium is the price of an option, per unit times the units. It buys the right and does not come back.
Notional, margin and premium are three different amounts
One scale. Margin and premium belong to two different positions.
Notional exposureThe size₹12,50,000
25,000 × 50. The size both positions refer to.
MarginFuture₹1,25,000
Assumed deposit for the future. 10× smaller than the size.
PremiumCall₹7,500
₹150 × 50. The price of one call, 0.6% of the size.
Hypothetical numbers.
Margin belongs to the future and premium to the call, so never add them. Contracts also trade in lots, the exchange’s fixed bundles of units. Lot sizes differ by instrument and change over time.
Can you lose more than the margin?
Why a small move is a big share of the margin, in both directions
 Marginthe small weightExposurethe large block
Yes. Margin lets you enter. It does not cap the loss.
The future’s value is ₹12,50,000 and its margin is ₹1,25,000, so the value is ten times the margin. A 1% move in the price, 250 points, is ₹12,500, which is 10% of the margin. That ratio is leverage.
It works in both directions. A 1% rise adds ₹12,500. A 1% fall takes ₹12,500. A 5% fall, to 23,750, takes ₹62,500, half the margin. If the price keeps falling, the exchange asks for more money, and the loss can pass the deposit.
A small move is a big share of the margin
Entry at 25,000 · 50 units · ₹1,25,000 margin.
Dashed line: the starting margin, ₹1,25,000. Grey: what is left of it.
Index 25,250 1% up
Index 24,750 1% down
Index 23,750 5% down
Three scenarios, not a range of possible losses.
A bought option is different. Its worst case is the premium, ₹7,500, so the buyer cannot lose more than that. Do not reuse the futures sums for it, because an option moves differently with the index. A seller of a call who holds nothing to cover it has no upper limit on the loss.
Who uses derivatives, and what for?
Maya a year on: the same tool, the other direction
To cancel out a risk, to take one on purpose, or to trade a price gap.
A year on, Maya’s restaurant has done well and she holds ₹10 lakh of shares. A big payment is due soon, and she does not want a fall to land just before it. Her worry is now the opposite of last year’s.
She can hedge: take a position that cancels out part of a risk she already carries. She sells a NIFTY future, so she goes short, and it gains when the index falls. A ₹10 lakh portfolio matches 40 units, because 40 × 25,000 = ₹10,00,000.
Say the index falls 1%, from 25,000 to 24,750, and her shares fall the same 1%. She loses ₹10,000 on the shares. The short future gains 250 × 40 = ₹10,000. The two cancel, before costs.
A hedge softens a loss. It does not remove it.
Maya a year on: a short future against her shares.
₹10 lakh of shares, hedged with a future sold at 25,000 (40 units) and bought back at 24,750, so the index falls 1%. Before costs.
Hypothetical numbers.
Real shares do not track an index exactly. If hers fell 2% while the index fell 1%, she would end ₹10,000 down. A hedge reduces a risk. It does not remove it, and it gives up gains when prices rise.
Speculation is taking a risk on purpose, to gain from a price move. Arbitrage is trading a gap between two related prices. Neither promises a profit. The words say what a position is for, not who holds it. The person on the other side of Maya’s hedge may be a speculator who has chosen to carry her risk.
How does a contract end?
An exit trade and an expiry obligation are different
You close it with an opposite trade, or you hold it to expiry and its settlement rules decide.
Before expiry, you close a position by trading the opposite side in the same contract: sell to close what you bought, buy to close what you sold. Only an executed trade closes it. An order that has not filled leaves the position open.
Only an executed opposite trade closes a position
Two routes from an open position.
These are Indian exchange rules.
If you hold to expiry, the contract’s rules decide. An index future or option settles in cash: only the money difference is paid, and no index is delivered. A stock future, or a stock option that finishes in the money, is settled in shares, so you may need to deliver or receive them. In the money means the option has intrinsic value. Lesson 38 covers settlement in full.
Before you go on, check you can say, for any contract: what it follows, the quantity, the expiry, your side, and whether the money you pay is margin or premium. Lesson 02 takes one futures contract from order to expiry.
Before you go
Check yourself
4 questions from this lesson. Pick an answer to see why, then slide on to the next.
Question 1 of 4

Questions readers ask
Common questions
What is a derivative in simple words?
It is an agreement whose value comes from something else, such as a share price or an index level. That something else is the underlying. Holding the agreement does not mean you own the underlying.
What is the main difference between futures and options?
A future binds both sides to go through with the deal. An option gives its buyer a right and its seller the duty. The option buyer pays a premium for that right.
Are margin, premium and notional value the same thing?
No. Notional value is the size of the position. Margin is security held against an obligation, and it does not cap a loss. Premium is the price of an option. In our examples the future’s assumed margin is ₹1,25,000 and the call premium is ₹7,500. They belong to different positions.
Can a call option lose money when the index rises?
Yes. At expiry the call’s value must also recover the premium. Our call has a 25,000 strike and a ₹150 premium. At 25,100 it is worth ₹100 per unit, so it loses ₹50 per unit: ₹2,500 on 50 units.
How do I close a futures or options position?
Make the opposite trade in the same contract: sell to close a bought position, buy to close a sold one. A different strike or expiry is a new contract. Until the trade executes, the position stays open.
What happens if I hold an Indian equity derivative to expiry?
Index derivatives settle in cash. Stock futures and in-the-money stock options are physically settled, so shares or funds may be needed. Check the contract, your side and your broker’s deadlines.