

Lesson 38
Derivatives Settlement: Cash vs. Physical Delivery
Follow the cash, shares and funding obligations of NSE index and stock derivatives at expiry.

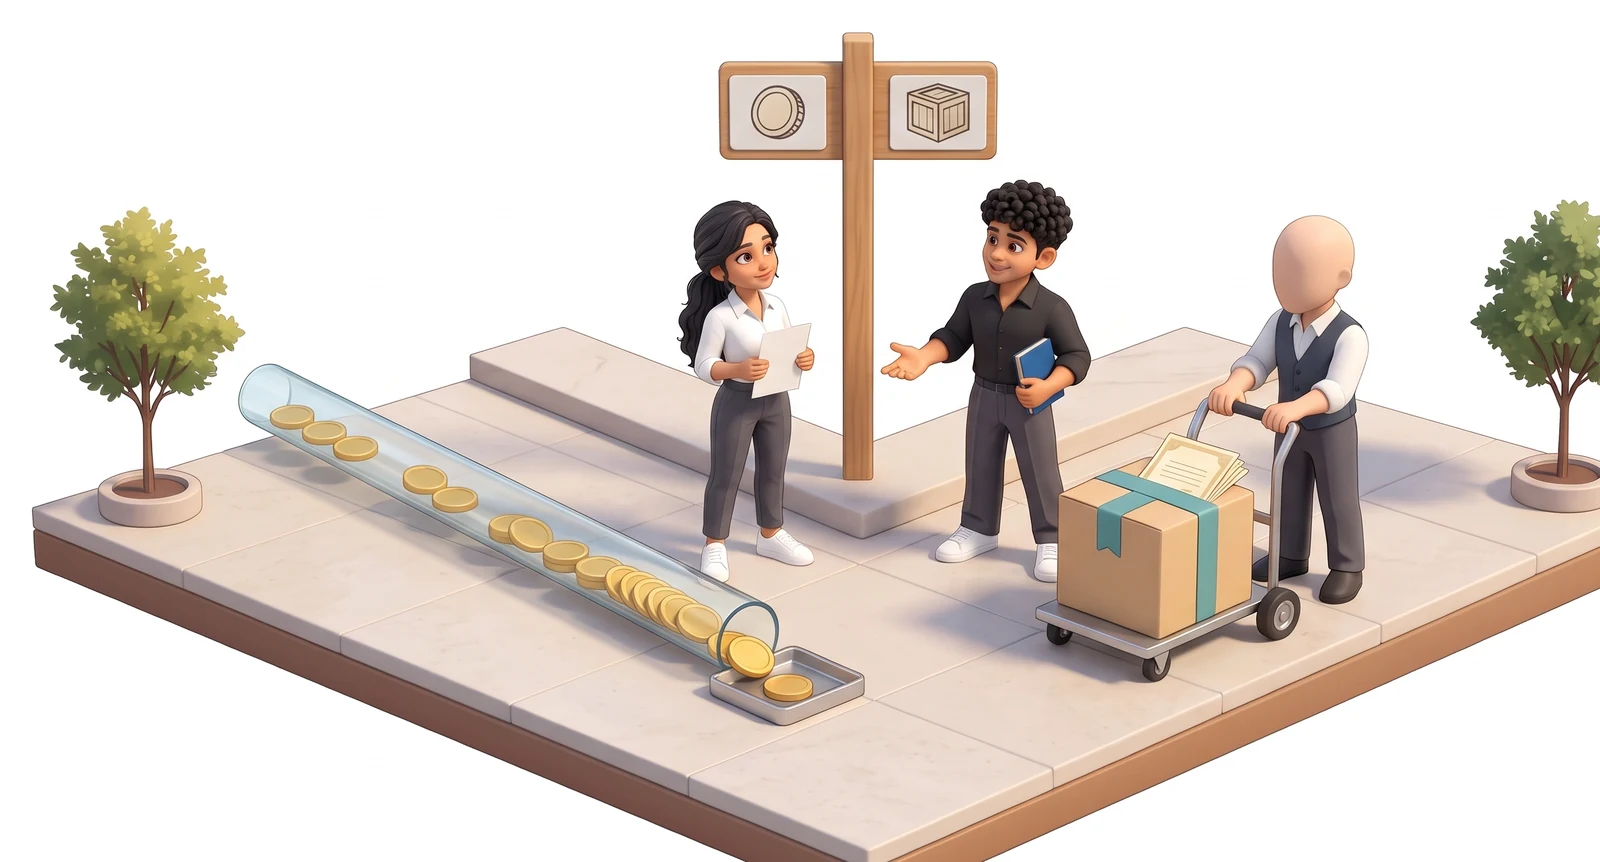

Index: cash. Stock: shares and cash.
| NIFTY callcash settlement | SBIN callphysical settlement | |
|---|---|---|
| Receive | ||
| Pay |
Separate constructed bought-call examples held through expiry · NIFTY 65 units · SBIN 750 shares · transfers and result differ
Follow the final obligation with Mr. Chartist
Read expiry as two account entries: money and shares. Name the contract and the position left open, then follow its settlement route to see what funding it needs.
By the end you will be able to answer
- Why is my final futures settlement different from the total profit shown?
- Does paying the premium fully fund an ITM stock Call at expiry?
- Do I need shares to settle a bought stock Put?
It is expiry day. You still hold a NIFTY option and an SBIN option. Both show a premium and a profit figure. But one will settle as a cash difference, and the other can ask you to pay for shares or deliver them from demat. Settlement is the step that completes whatever is left.
So what must move in or out of your account if the position stays open? We follow money and shares, and keep margin apart from payment. Being in the money tells you the exercise value. It does not tell you your profit.
The lesson covers NSE equity derivatives cleared by NSE Clearing, with rules checked on 8 October 2026. The prices, premiums and quantities, including 65 NIFTY units and 750 SBIN shares, are constructed inputs. They are not live quotes or current lot sizes. For the share side of settlement, see Clearing and T+1 settlement; for the calendar, Settlement and market timings.
Updated
Two ways an expiring contract is settled
Compares cash settlement with physical settlement.

My NIFTY Call finishes 50 points in the money. Do I get index shares?
No. An expiring contract ends in one of two ways. Cash settlement moves only a calculated sum of money. Physical settlement moves shares and money.
And which one is mine?
NIFTY index contracts settle in cash: 50 points on 65 units is ₹3,250. Open stock futures, and stock options exercised in the money, create delivery obligations.
So the premium is not a prepayment for the shares?
Right. The premium bought the contract. Funds and shares for delivery must be ready on their own.
An expiring contract ends in one of two ways. Cash settlement moves only a calculated sum of money. Physical settlement moves shares and money. The option premium you paid bought the contract; it is not a prepayment for either route.
Look at the underlying first. NSE index contracts settle in cash. Open stock futures, and stock options exercised in the money (ITM), create delivery obligations. Intrinsic value is the positive exercise value at the final reference price, before premium and costs. Two bought Calls show the difference.
Two bought Calls, two settlement routes
Follow what actually moves at expiry. The index route pays intrinsic cash; the stock route exchanges the strike payment for demat shares.
Bought NIFTY 50 Call
Strike 25,000 · final index 25,050 · assumed 65 units
(25,050 − 25,000) × 65 units
This ₹3,250 receipt is before subtracting the ₹6,500 entry premium. Buyer’s result: −₹3,250 before costs.
No index units are delivered. This bought-option example does not describe the cash obligations of index option writers or futures positions.
Bought SBIN Call
Strike ₹820 · final reference ₹822 · assumed 750 shares
₹820 × 750 shares; entry premium paid separately
Marked at ₹822 each: ₹6,16,500 at the final reference
The shares’ marked value exceeds the strike payment by ₹1,500. After ₹10,500 entry premium, the marked result is −₹9,000 before costs.
There is no additional ₹1,500 cash credit. The buyer must fund delivery; the shares remain exposed to prices after settlement.
A positive intrinsic value does not establish a profit. Separate the premium already paid, the settlement transfer and the value of shares received.
NSE equity-derivatives scope, checked 8 October 2026. Prices and quantities are constructed assumptions, not live quotes or current contract-size specifications. Gross isolated obligations are shown; eligible member/client/security netting, the published settlement calendar and the broker’s funding deadlines determine the actual obligation.
Consider a bought NIFTY 50 Call with a 25,000 strike, a ₹100 premium per unit and an assumed quantity of 65. If the official final index reference is 25,050, its positive intrinsic value is 50 points per unit. The holder receives ₹3,250 through cash exercise settlement. No basket of NIFTY companies or index ETF is delivered. The ₹6,500 premium was paid separately, so the option result is −₹3,250 before costs.
The matching Call writer owes the ₹3,250 exercise payment. A futures position can also owe cash MTM, depending on its side and the price change. Cash settlement removes share delivery; it does not remove settlement funding, margins or charges for every participant. Conversely, an out-of-the-money stock option has no exercise delivery. Its premium result remains, but a stock contract does not deliver shares merely because it existed.
Use the official final reference
Shows which price settles an expiring contract.
One official price settles the contract. For an option, it decides whether there is intrinsic value: a Call is in the money when that price is above the strike, and a Put when it is below. A last traded price on your screen is not that price, and neither is an indicative auction price while orders are still being matched.
The 2026 closing-auction rules decide how the price is formed. Under SEBI’s 16 January 2026 circular, index derivatives settle on the underlying index close, worked out from the closing prices of its constituents. Stock derivatives settle on a clearing-corporation price, based on the volume-weighted average of the stock’s closing prices across exchanges. So the stock reference is not simply “the last NSE trade”.
The Closing Auction Session, or CAS, runs 15:15 to 15:35 for cash stocks that have derivatives. Its equilibrium gives the cash closing price, with a stated fallback if no equilibrium forms. NSE’s regular derivatives session runs until 15:40. These are separate rules, so the old habit of reading the 15:30 tick no longer explains settlement.
Our ₹822 SBIN reference is an assumed number, not a real auction. With it fixed, a Call struck at ₹820 has ₹2 of intrinsic value per share. The reference decides whether the option is exercised and its value. The share payment still uses the ₹820 strike. Daily futures settlement is a separate calculation again.
Settle only the remaining futures MTM
Pays only what is still owed on a futures position.
Final futures settlement pays only what is still owed. Futures gains and losses are settled every day through mark-to-market, or MTM. The last step completes that running account. It does not pay the whole entry-to-expiry result a second time. A position carried over starts from the previous settlement price; a position opened on expiry day starts from its trade price.
Final MTM settles only the remaining price change
Earlier mark-to-market (MTM) cash has already settled. Compare the final reference with the previous settlement price for the remaining cash leg, then reconcile the total from entry.
NIFTY long future
Earlier MTM · already settled+₹6,500- Remaining final MTM · cash credit+₹3,250
- Total futures result+₹9,750
A reconciliation, not an extra payment. No share delivery.
SBIN long future
Earlier MTM · already settled+₹7,500- Remaining final MTM · cash credit+₹7,500
- Total futures result+₹15,000
Separately: pay ₹6,30,000 and receive 750 SBIN shares.
NIFTY 50 long future
- Entry · index points
- 25,000
- Previous settlement · index points
- 25,100
- Final reference · index points
- 25,150
- Assumed quantity
- 65 units
SBIN long future
- Entry · per share
- ₹820
- Previous settlement · per share
- ₹830
- Final reference · per share
- ₹840
- Assumed quantity
- 750 shares
NIFTY’s remaining cash credit is ₹3,250, not its ₹9,750 total result. SBIN’s remaining cash credit is ₹7,500; its ₹15,000 total is a reconciliation, not an extra payment. The SBIN long separately pays ₹6,30,000 and receives 750 shares. That principal buys the delivery asset; it is not a trading loss.
Hypothetical prices and assumed quantities, not live quotes or current lot specifications. NSE/NCL settlement scope checked 8 October 2026 against the NCL consolidated F&O circular dated 30 April 2026, Part B §§3.1, 5.1 and 5.4. These are gross isolated positions before eligible netting, fees and taxes; margin release is not shown. Shares received remain exposed to later prices. The short future has opposite MTM signs and the reciprocal stock delivery.
Reconcile the MTM cash and delivery principal
The earlier cumulative amount can span several daily settlements. The final cash difference begins at the previous settlement price; the total begins at entry. Stock futures delivery uses the final settlement reference.
NIFTY earlier MTM = (25,100 − 25,000) × 65 = ₹6,500NIFTY remaining MTM = (25,150 − 25,100) × 65 = ₹3,250NIFTY total = ₹6,500 + ₹3,250 = ₹9,750SBIN earlier MTM = (₹830 − ₹820) × 750 = ₹7,500SBIN remaining MTM = (₹840 − ₹830) × 750 = ₹7,500SBIN total = ₹7,500 + ₹7,500 = ₹15,000SBIN delivery principal = ₹840 × 750 = ₹6,30,000; receive 750 shares
Take a long NIFTY 50 future entered at 25,000, settled the day before at 25,100 and finally settled at 25,150, for 65 units. Earlier MTM was ₹6,500. The last 50 points pay ₹3,250. The total result before costs is ₹9,750. Calling ₹9,750 the final payment would count the ₹6,500 twice. A short position has the opposite signs.
A stock future adds a delivery obligation. Our SBIN long future starts at ₹820, settles at ₹830 and finally at ₹840, for 750 shares. Earlier MTM is ₹7,500 and the final MTM is another ₹7,500, so the futures result is ₹15,000 before costs. Separately, the delivery costs ₹840 × 750 = ₹6,30,000.
That payment uses the final settlement price, not the ₹820 entry. The ₹15,000 and the shares answer different questions. A short stock future delivers the shares and receives ₹6,30,000, with the opposite MTM. Any gain or loss on shares you already own needs its own cost, and cannot be read from the future.
A small intrinsic value can accompany a large payment
Separates premium, intrinsic value and the delivery payment.
Back to the SBIN Call: ₹820 strike, ₹14 premium per share, 750 shares, final reference ₹822. Treat it as one bought position with nothing to net against. Premium, delivery payment, intrinsic value and profit are four different amounts. Keeping them apart shows why “in the money” does not mean “profitable” or “fully funded”.
The premium payment was ₹10,500. Automatic exercise requires the holder to pay ₹6,15,000 and receive 750 shares at the strike. The shares are worth ₹6,16,500 when marked at the assumed ₹822 reference. Their ₹1,500 excess over the strike payment is the Call’s intrinsic value. Physical settlement does not also credit another ₹1,500 as an index-style cash exercise payment.
Delivery funding and option result answer different questions
A bought Call held through expiry: ₹820 strike, ₹14 premium per share, 750 shares and a ₹822 final reference.
What the Call buyer exchanges at delivery
- Cash paid for the shares
- ₹6,15,000
Strike × quantity. This is the delivery payment, exchanged for shares.
- Shares received in demat
- 750 shares
Marked at ₹822 each, their value is ₹6,16,500 at the final reference.
- Margin and collateral
- Tracked separately
The delivery payment is not a margin estimate. Verify the applicable margin and funding requirements with the broker.
What the option is worth after its premium
- Premium paid earlier
- ₹10,500
Premium per share × quantity; separate from the delivery payment.
- Intrinsic value at the reference
- ₹1,500
Marked share value less strike payment. This is not an additional cash credit.
- Economic option result before costs
- −₹9,000
Intrinsic value less the premium paid. An in-the-money Call can still lose money.
The ₹6,15,000 payment buys an asset; it is not itself a loss. The ₹1,500 intrinsic value is already represented by receiving shares worth more than that payment, so adding a separate intrinsic cash receipt would double-count it.
Hypothetical NSE/NCL stock-option example, with assumed quantity; one isolated position before eligible netting, taxes and other costs. This is an expiry-reference valuation, not a realised share-sale result. The shares remain exposed to later price changes. Physical-delivery basis: NCL consolidated F&O circular, 30 April 2026, Part B §5.4, checked 8 October 2026; linked in the lesson sources.
After deducting the ₹10,500 premium, the option’s marked economic result is −₹9,000 before charges. This is a loss despite positive intrinsic value. It is also separate from the ₹6,15,000 principal required for the purchase. The principal buys an asset; it is not all a trading loss. A later share sale can realise a different combined outcome because the share price and selling costs may change after expiry.
For comparison, suppose this same bought Call had instead been fully sold to close at an assumed ₹41 premium per share before expiry. Its sale proceeds would be ₹30,750 and its completed option result ₹20,250 before costs. Those are separate constructed outcomes, not an available exit promised alongside the ₹822 expiry case. A confirmed closing fill removes the residual obligation for its filled quantity. An unfilled order, or a broker’s attempted square-off, does not establish that the position has closed.
Follow the shares and funds for each position
Traces who pays and who delivers for each position.
Who pays and who delivers depends on the position you hold. In a stock option, the in-the-money buyer exercises, and a writer is assigned the opposite side. Work out each gross obligation first, before you combine anything. The routes below assume the option reaches exercise or assignment, and leave out premium and charges.
Six stock positions, two delivery directions
Each row assumes 750 shares. Futures use the ₹840 final reference. Separate ITM option cases use a ₹820 strike: Call final ₹822, Put final ₹818.
| Stock position held | Share movement | Delivery cash movement | Delivery price basis |
|---|---|---|---|
| Long stock future | Receive 750 shares | Pay ₹6,30,000 | ₹840 final reference × quantity |
| Short stock future | Deliver 750 shares | Receive ₹6,30,000 | ₹840 final reference × quantity |
| Long ITM Call | Receive 750 shares | Pay ₹6,15,000 | ₹820 strike × quantity |
| Short ITM Call | Deliver 750 shares | Receive ₹6,15,000 | ₹820 strike × quantity |
| Long ITM Put | Deliver 750 shares | Receive ₹6,15,000 | ₹820 strike × quantity |
| Short ITM Put | Receive 750 shares | Pay ₹6,15,000 | ₹820 strike × quantity |
Receive shares means pay the delivery principal; deliver shares means receive it. A Put buyer therefore needs deliverable shares. Cash paid or received is an asset-exchange leg, not the position’s profit or loss. All open deliverable futures qualify; ITM is an option exercise condition.
Hypothetical prices and assumed quantity; gross obligations for separate positions, before eligible same-security/member/client netting and costs. Futures remaining cash MTM settles separately from this delivery principal; previously settled MTM is not paid again. Option premium is a separate cash flow. Margin and collateral are tracked separately, and do not establish the economic result. OTM or exactly ATM options create no exercise delivery. Source: NCL consolidated F&O circular, 30 April 2026, Part B §§5.2–5.4, checked 8 October 2026; linked in the lesson sources.
A bought in-the-money Call receives shares and pays strike × quantity. A sold in-the-money Call delivers the shares and receives that payment. At the ₹822 reference, both sides swap 750 SBIN shares for ₹6,15,000. The writer’s option result is +₹9,000 before costs, the mirror of the buyer’s −₹9,000. That is not the writer’s whole profit, because the cost of the shares delivered also counts.
Now a Put with the same ₹820 strike, ₹14 premium and 750 shares, and a final reference of ₹818. The bought Put delivers shares and receives ₹6,15,000. The sold Put pays that and receives the shares. Intrinsic value is ₹1,500, less than the ₹10,500 premium, so the buyer’s result is −₹9,000 before costs. The sale receipt is not profit.
The last two routes are stock futures. A long future receives shares and pays the final settlement price × quantity; a short delivers and receives it. Futures have no in-the-money test. In all six routes, usable funds, deliverable shares and authorisation have to be ready. A demat holding or a collateral figure does not fulfil them automatically.
Delivery margin prepares for the obligation
Shows how delivery margin builds up before expiry.
The premium buys the option. Delivery margin secures the share settlement that might follow. From four trading days before expiry, NSE Clearing stages a delivery margin on eligible stock-option buy positions. It covers the lower of the potential deliverable positions and the in-the-money long options, judged on that day’s closing cash price. It is not one schedule for every future and writer.
The amount uses the share’s capital-market Value at Risk, Extreme Loss and Additional Margin rates. Long options in the money are valued at strike, other marginable positions at the closing price. The result is a risk figure. It is not the premium and not a fixed share of contract value, and for a portfolio it reflects your eligible offsets.
Delivery margin is staged; share payment is separate
E is the expiry day. Count trading days backwards; each checkpoint below is end of day. The percentages apply to the computed delivery margin D, not to the full value of the shares.
- E−4 · end of day₹10,000
10% of D, in total at this checkpoint.
- E−3 · end of day₹25,000
25% of D, in total at this checkpoint.
- E−2 · end of day₹45,000
45% of D, in total at this checkpoint.
- E−1 · end of day₹70,000
70% of D, in total at this checkpoint.
Base for this staging illustration
- Assumed full computed delivery margin · D
- ₹1,00,000
Held constant here to isolate the schedule. This is a supplied teaching input, not an actual SBIN margin rate or broker requirement.
Separate unnetted SBIN Call delivery
- Cash payment if the bought Call is exercised ITM
- ₹6,15,000
₹820 strike × 750 shares. This buys the shares; margin or collateral alone does not establish that this payment is funded.
These are total requirements at each checkpoint, not amounts to add together. The final row is ₹70,000, not the sum of all four rows. Actual D is recomputed from positions, prices and applicable rates each day. After expiry, converted delivery positions face a separate capital-market Value at Risk (VaR), Extreme Loss Margin (ELM) and mark-to-market (MTM) delivery-margin regime; there is no “100% of share value” row in this exchange ramp.
Scope: NCL applies this pre-expiry schedule at client level to the lower of potential deliverable positions and in-the-money long stock-option positions, with ITM determined from the underlying capital-market closing price. Futures and option writers retain their ordinary applicable derivatives margins; this table is not their universal margin schedule. Brokers can require more or intervene earlier. The SBIN price and quantity are teaching assumptions, before eligible netting and separate costs. Source: NCL consolidated F&O circular, 30 April 2026, Part B §10.2.7, checked 8 October 2026; linked in the lesson sources.
To see the staging alone, assume the full delivery margin D stays at ₹1,00,000. At the end of E−4, E−3, E−2 and E−1 the requirement is 10%, 25%, 45% and 70% of D: ₹10,000, ₹25,000, ₹45,000 and ₹70,000. Each is the total at that point; they are not added together. Neither the percentages nor D are real SBIN rates, and D can change every day.
E is the actual expiry trading day, so holidays move the count. After expiry, positions that turn into delivery face the capital-market VaR, Extreme Loss and MTM delivery margins. There is no ramp row saying “100% of share value”. Paying for the shares in full is a different matter from margin, and your broker may ask for it separately. Futures and writers keep their derivatives margins too.
Your broker can ask for more, include positions near the strike, and set an earlier funding or exit deadline. It cannot promise a fill. A blocked ₹70,000 is not a ₹70,000 loss, and it does not mean the ₹6,15,000 purchase is funded. Pledged shares secure margin. Check separately that cash is available, or that shares are deliverable and authorised.
Exercise, eligible netting and the settlement day
Follows exercise, netting and the settlement day.
NSE equity options are European style, so they are exercised only at expiry. Options with positive intrinsic value are exercised automatically and assigned to writers of the same series. Do Not Exercise for stock options ended from March 2023 expiry. Missing funds or shares do not cancel an exercise. Options exactly at the strike, or out of the money, have no exercise delivery.
After exercise, eligible obligations are combined in two ledgers, shares and funds. Netting needs the same security, clearing member, trading member and client UCC, with the matching expiry or trade date and settlement. One PAN, one app, or a hedge at another broker does not meet these tests. Some institutional and PMS delivery-backed clients are excluded from cross-segment netting. Shares you already hold can supply delivery if usable and authorised.
Net shares and net funds are separate balances
Buy the ₹820 Call at ₹14 and sell the ₹840 Call at ₹6 per share; 750 shares on each leg. Both contracts remain open. Compare two official final references, assuming these obligations qualify for netting.
Final reference ₹850
Both Calls in the money
- Bought ₹820 Call+750 shares
Receive shares; pay ₹6,15,000
- Sold ₹840 Call750 shares
Deliver shares; receive ₹6,30,000
- Net share obligation0 shares
- Net exercise funds, before premiumReceive ₹15,000
₹6,30,000 − ₹6,15,000
- Economic result, before costs+₹9,000
₹15,000 − ₹6,000 net premium
Final reference ₹830
Only the bought Call in the money
- Bought ₹820 Call+750 shares
Receive shares; pay ₹6,15,000
- Sold ₹840 Call0 shares
Out of the money: no shares or funds
- Net share obligation750 shares
- Net exercise funds, before premiumPay ₹6,15,000
No exercise funds receipt
- Economic result, before costs+₹1,500
₹6,22,500 share value − ₹6,15,000 − ₹6,000 premium
The net entry premium was ₹6,000. At ₹850, equal share obligations offset but leave a ₹15,000 funds receipt. At ₹830, the OTM sold Call supplies no offset: the bought Call requires ₹6,15,000 to receive 750 shares. Its ₹7,500 intrinsic value is represented by the shares, not extra cash. A capped intact spread payoff does not remove delivery funding.
Hypothetical prices and assumed quantity, not live quotes or a verified current lot. NSE/NCL eligibility requires the same security, clearing member (CM), trading member (TM) and client/UCC; expiry obligations must correspond to the applicable capital-market trade date and settlement type/number. No other eligible obligations are assumed here. Premium, taxes, other costs and margin are distinct from these exercise balances; zero net shares does not remove charges. Actual broker pre-settlement funding can be higher than the net funds obligation. Verify the final client-level obligation and broker deadlines. The ₹830 result marks delivered shares at the final reference, before costs; later prices and any sale execution change the realised result. Basis: NCL consolidated F&O circular, 30 April 2026, Part B §§5.3–5.4, checked 8 October 2026; linked in the lesson sources.
Try an SBIN spread: buy the ₹820 Call at ₹14, sell the ₹840 Call at ₹6, 750 shares each, same expiry, all netting conditions met. At a ₹850 final reference both Calls are in the money. You receive and deliver 750 shares, so net shares are zero. The two strike payments leave ₹15,000 received. After the ₹6,000 entry debit, the result is ₹9,000 before costs.
At a ₹830 reference only the bought ₹820 Call exercises. The sold ₹840 Call is out of the money and offsets nothing. You receive 750 shares and owe ₹6,15,000, though the spread’s economic result is only ₹1,500 before costs. A capped payoff does not mean a small funding need. Different strikes remain separate contracts, and only confirmed closing fills reduce them.
Net physical obligations settle on the next capital-market settlement day (T+1), skipping weekends and holidays; the published calendar controls. See Clearing and T+1 settlement. A clearing member’s pay-in time is not your deadline: your broker can ask for funds, shares or authorisation earlier. What you must meet is your own net obligation, not a member-level offset. Reports can be revised after custodial confirmation, so use the final statement.
Share shortages and funds shortages follow different paths
Compares what happens with a share shortage and a funds shortage.
If you owe shares and do not deliver them, that is a securities shortage. It can come from a bought stock Put, a sold stock Call or a short stock future. NSE Clearing sends applicable shortages to a buy-in auction, and charges the auction cost to the short-delivering member. If the auction fails, the shortage can end in financial closeout. Some corporate-action shortages go straight to closeout.
The auction cost is not a fixed fee quoted in advance. For an unfilled shortage in the normal market, closeout uses the higher of two prices: the highest price across exchanges from trading through auction day, and 120% of the auction-day settlement price. It is not a flat 20% penalty. The first valuation debit is not the final bill, and other kinds of shortage have their own rules.
Owing money is a different failure. A bought Call or sold Put that cannot pay for the shares faces a funds shortfall, not an auction. Your broker’s funding, liquidation and recovery terms apply, and neither a sale nor its price is promised. Delivery failures can cost more than the option’s intrinsic value or premium, depending on the shortage, the remedy and the market.
A nearby strike is an exercise boundary
Shows how a nearby strike sets the exercise line.
Near the strike, a tiny price difference can switch delivery on or off. This is often called pin risk. For the ₹820 SBIN Call, a final reference of ₹819.90 has no intrinsic value. At ₹820 it is also zero. At ₹820.10 the Call is in the money, with just ₹75 of intrinsic value for 750 shares, yet it creates the full ₹6,15,000 purchase obligation.
The uncertainty lasts while the official reference is being formed and confirmed. A buyer does not choose after expiry. The CAS timing, broker cutoffs, available data and execution are separate things, and a screen LTP can sit on the other side of the strike from the official reference.
Know your route before it matters. A bought Call or sold Put needs funds to receive shares. A bought Put or sold Call needs shares to deliver. An index option pays an intrinsic cash amount, and writers owe it. An unfilled close order resolves nothing, and a roll opens a new contract after closing the old one. What settles is what is actually open.
Separate the tax event, its base and its payer
Keeps the tax event, its base and its payer apart.
Securities Transaction Tax (STT) depends on the event: trading, exercise, or physical delivery. From 1 April 2026, selling an option in the market attracts 0.15% on premium × quantity, paid by the seller. Exercising an in-the-money option attracts 0.15% on positive intrinsic value × quantity, paid by the option buyer. Selling futures attracts 0.05% on trade price × quantity, paid by the seller.
Exercise STT has used intrinsic value, not the full settlement price, since September 2019. The old warning that exercise STT is charged on full notional is out of date. In our stock Call case, ₹1,500 of intrinsic value gives ₹2.25 of exercise STT before aggregation and rounding. That is not the whole physical-settlement bill, and the option was already losing before tax.
Physically settled stock futures and options also attract delivery STT of 0.10%, paid by both the receiver and the giver of shares. Stamp duty, brokerage, exchange charges, taxes on services and depository charges can add more. Each has its own base and rate, and netting does not erase a tax event. A full rupee estimate needs the contract note. Brokerage, charges and taxes explains each line.
Selling or letting it expire is not always cheaper. Sale premium, final intrinsic value, execution and charges can all differ. For a real contract, confirm the listed quantity and expiry, the current final-price rule, the margin, your net share and funds obligation, and your broker’s deadlines. Check them against confirmed fills and usable holdings. The next lesson turns these events into tax treatment.
Before you go
Check yourself
5 questions from this lesson. Pick an answer to see why, then slide on to the next.
Question 1 of 5

Questions readers ask
Common questions
Why is my final futures settlement different from the total profit shown?
Mark-to-market (MTM) settles futures price changes along the way. Remaining expiry MTM compares the final settlement price with the previous settlement price, or the trade price for a newly opened expiry-day position. Earlier MTM enters the total result once. Stock futures also have a separate shares-and-payment obligation, valued at the final settlement price.
Does paying the premium fully fund an ITM stock Call at expiry?
For an unnetted bought stock Call exercised in the money (ITM), you receive shares and pay strike price × delivered quantity. Premium does not automatically fund that purchase. Small intrinsic value can accompany a large principal payment and a loss after premium and costs. Confirm usable funds, the net obligation and your broker’s deadline; pledged collateral alone does not establish available payment.
Do I need shares to settle a bought stock Put?
An exercised ITM bought stock Put requires shares against receipt of strike price × quantity, before eligible netting and charges. Buying the Put does not supply those shares. Check deliverable holdings and transfer authorisation against your broker’s deadline. A share shortage can enter auction or closeout. A take-delivery funds shortage is a different failure, not automatically a share auction.
Can I use Do Not Exercise if I lack delivery funds or shares?
NCL’s stock-option Do Not Exercise facility ceased from March 2023 expiry. Missing funds or shares do not cancel automatic ITM exercise. These options are European style: final exercise occurs at expiry. Reconcile confirmed closing fills and remaining quantity. Neither an exit request nor a broker’s intended intervention establishes that the position closed.
What happens if the official final price equals my strike exactly?
Exactly at the strike, intrinsic value is zero and there is no positive-intrinsic exercise obligation. Use the official final reference, rather than screen LTP or indicative auction value. A near-strike option can finish ITM or OTM. Current NSE closing-auction rules supersede old universal 15:30 or final-half-hour shortcuts. Broker near-strike margin treatment is separate from final exercise status.
Will a stock-option spread or a hedge at another broker remove delivery?
Eligible netting requires the same security, clearing member, trading member and client/UCC, with the corresponding expiry/trade date and settlement. An unrelated broker does not automatically qualify. An OTM leg supplies no exercise delivery to offset the ITM leg. Zero net shares can still leave funds and charges. Check the client-level net obligation, rather than relying on a strategy label.
Does the delivery-margin ramp mean I have already paid for the shares?
No. NCL’s staged percentages for eligible stock-option buy positions apply to computed delivery margin, not full share value. Each stage states the requirement; do not add them together. Positions, prices and risk rates can change the base. Post-expiry delivery margins follow a separate framework. Check full funds or deliverable shares separately; broker requirements and operational cutoffs can be stricter.
Which STT base and settlement deadlines should I verify?
Exercise STT uses positive intrinsic value, at 0.15% from 1 April 2026. Market option sales use premium; physical stock settlement adds a separate delivery-STT layer. Netting does not erase tax events. Check other charges against the tariff. T+1 follows the applicable settlement working-day calendar. Verify your broker’s client deadlines separately: a clearing-member pay-in cutoff is not a universal retail funding or demat deadline.