

Lesson 32
Margin, Leverage & Pledging
Margin is a deposit, leverage makes every move bigger, a margin loan charges interest every day, and pledged shares count for less and fall with the market. One real week on one real share shows all four.

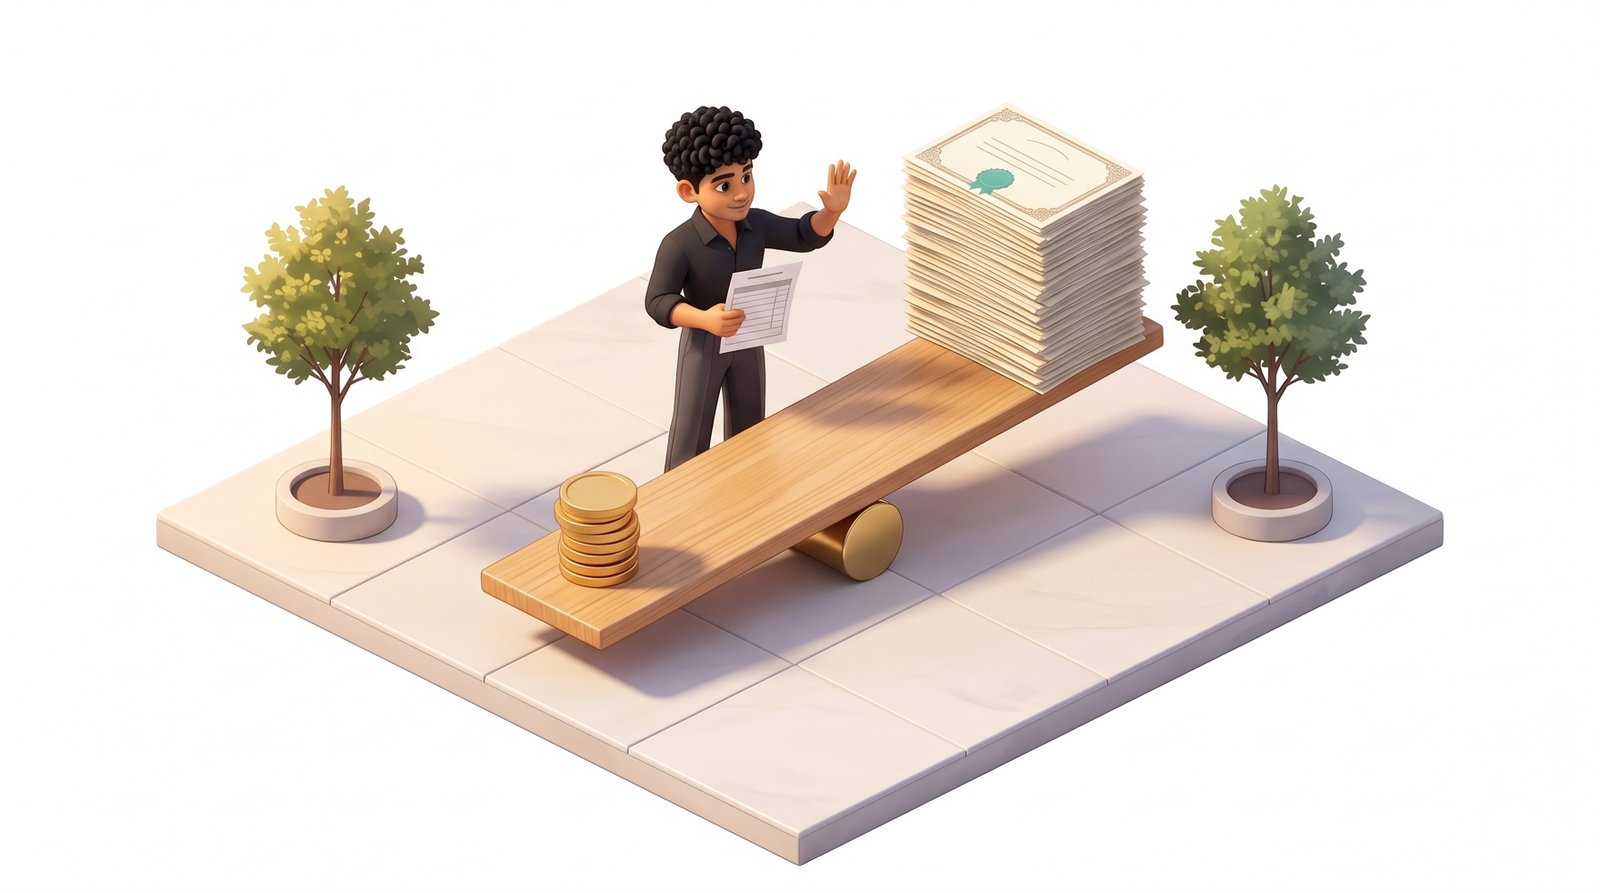
Margin trading means buying shares with part of your own money and part borrowed from your broker, with shares pledged as security. Every price move becomes bigger on your own money, both ways. You pay interest. And if the price falls, the broker can ask for more money within days, or sell your shares.
On Friday 16 October 2026, shares of Lodha, the Mumbai property developer, closed at ₹1058.70 on NSE. A week later they closed at ₹963.00, 9.04% lower. Ten shares bought with ₹10587.00 of your own money lost ₹957.00. The same ₹10587.00 on the most a broker could lend carried 37 shares, lost ₹3540.90, and was short of margin after one trading day.
By the end you will be able to answer three questions: what margin is, and how much bigger leverage makes a move on your own money; how a margin loan (MTF) or a pledge of your shares works, and what it costs; and what happens when the price falls: who asks for money, by when, and who sells.
Maya, who runs a burger restaurant and is learning to invest, is made up, and so are her amounts and the rule she writes in chapter 8. Every trade on this page is an illustration on real prices, not a trade anyone made. Lodha, Zee Entertainment and Archegos are real, and every price comes from the daily records of NSE (the National Stock Exchange of India), with the date; every rate comes from the clearing corporation's or the regulator's own files. Amounts are in Indian rupees (₹): one lakh is 100000 and one crore is 10 million. India's rules are named as India's; where the US differs, we say so. Where we do our own arithmetic, we say derived.
Margin Holds a Position
A deposit that holds a position bigger than your money
After the lunch rush, Maya opens her trading app and sees a banner: five times her money for intraday. When she planned her restaurant in why the stock market exists, she turned down a bank loan, because it wanted fixed payments every month whatever her dining room did.
My app says I can buy five times my money for intraday. Is that the bank loan I refused, in a new form?
Close. If you buy five times your money, who pays for the other four parts?
The broker, I suppose. Until I sell the same day.
And if the price falls 2%, whose account takes the fall on all five parts?
Mine. So my money is only the deposit, and the loss is on everything.
That is margin. Let's read what it is made of, on one real share and one real week.
Margin is money, or shares, you put down as a deposit against a position. The position, also called exposure, is the full value you control: the number of shares times the price. The position decides the gain or the loss; the deposit only decides how big a position you may hold.
(made up) at on Friday 16 October 2026. Paid in full, it buys 10 shares. With a margin loan, it can hold up to 37 shares, worth ₹39171.90. Intraday at five times, it can hold 50 shares, worth ₹52935.00, which must be closed the same day. The same money, three sizes of position (derived).
Figure 1Margin
The same ₹10587.00 holds 10, 37 or 50 Lodha shares
 Lodha · ₹1058.70NSE close, Fri 16 Oct 2026 · the price of one share
10 × ₹1058.70 = ₹10587.00
Her money ₹10587.0010 shares · no loan₹10587.00
37 × ₹1058.70 = ₹39171.90
Her money ₹10587.00 + lent ₹28584.90
The rate allows up to 3.75 times; shares come whole, and 38 would need ₹10717.43, so 37 is 3.70 times.37 shares · 3.70 times her money₹39171.90
50 × ₹1058.70 = ₹52935.00
Her money ₹10587.00 + carried ₹42348.0050 shares · 5 times her money₹52935.00
The gain or the loss follows the whole bar, not the dark part.
Margin comes in three forms. Intraday, often called MIS: the broker carries the rest only until the close (placing your first order shows the product box). MTF, the margin trading facility: India's regulated broker loan for buying shares to hold, with interest (chapter 4). A margin pledge: shares you already own, locked so they count as margin (chapter 5). Futures and sold options also run on margin; the Options course explains those.
for the multiple: exposure divided by your own money. 50 shares on ₹10587.00 is five times; 37 shares is 3.70 times.
In the US this is called buying on margin: the Federal Reserve's Regulation T lets you borrow up to half the price of a share. The words differ by country; the idea is the same.
Why five times for intraday, but less for the loan? Who decides the deposit?
Reading the Margin Parts
Who decides the deposit, and why the multiple differs by product

Does my broker just pick a number for the deposit?
It starts from a file the clearing corporation publishes every day, one line per share.
So the same share can need different deposits?
Yes: 20% for intraday on Lodha that day, 26.64% for a loan. Divide one by the rate: 20% gives five times.
Every day NSE Clearing, the clearing corporation that guarantees NSE's trades, publishes a margin file with one line per share. Lodha's line at the start of Friday 16 October 2026 read, in part: LODHA, EQ, … 16.14, 0.00, 16.14, 3.50, 0.00, 19.64. The last six numbers are percentages: the share's own VaR, the index's VaR, the VaR margin, the ELM, any extra (adhoc) margin, and the total that applies. The next two paragraphs explain the ones that matter.
VaR margin, 16.14%, comes from value at risk: the clearing corporation's estimate of a large one-day fall for this share, worked out from its recent swings. A calmer share has a smaller VaR. ELM, 3.50%, is the extreme loss margin, a fixed extra cushion for a fall bigger than VaR expects. , 19.64%, is the two added together.
Figure 2The margin parts
One line of a clearing file
LODHAEQ…16.14share's VaR, 16.14%The share's own value at risk, from its recent swings.share's VaR
0.00index VaR, 0.00%Used for shares too thinly traded to have their own; zero here.index VaR
16.14VaR margin, 16.14%The VaR margin the clearing corporation applies.VaR margin
3.50ELM, 3.50%Extreme loss margin: a fixed extra cushion.ELM
0.00adhoc, 0.00%Any extra margin the clearing corporation adds; none that day.adhoc
19.64total, 19.64%VaR margin plus ELM: the exchange's number.total
For intraday, India's rule has a floor: in the cash market a broker must collect at least 20% of the trade's value up front. Lodha's 19.64% is lower, so 20% applies, and one divided by 20% is the five times in Maya's app (derived).
A margin loan asks more. For MTF on a share that also has futures, the rule is VaR plus three times ELM: 16.14 + 10.50 = 26.64%, and never less than 20%. So the biggest position a margin loan could hold on Lodha that day was 3.75 times the deposit (derived). need VaR plus five times ELM.
Brokers may ask more than these minimums, never less, and the rates move every day: Lodha's VaR margin was 16.04% to 16.14% that week. Since 1 December 2020, phased in until 1 September 2021, the clearing corporation also checks each client's margin at least four times a day at random moments, called peak margin; the deposit must be there at the highest one, not only at the close. In the first phase a client could still carry up to 20 times for intraday; from 1 September 2021, at most five times.
Figure 3The margin parts
The same line sets three deposits
So at five times, what does one ordinary bad day do to my money?
Leverage: The Same Move, a Bigger Position
The move on your money is the move on the share times the leverage, both ways
A 4% fall doesn't sound like much.
On the share, no. At five times, it is about a fifth of your deposit.
And on a good day?
The same size, the other way. Leverage doesn't pick a side.
: the move on your money equals the move on the share times the leverage, before charges.
A down day first, Friday 23 October 2026 (an illustration on real prices). Say Maya takes the app's offer at the open: 52 Lodha shares at ₹1003.10, ₹52161.20 of exposure on ₹10432.24 of margin (20%). , ₹941.00, the share was 6.19% down and her position ₹3229.20 down: 30.95% of her deposit. At the close, ₹963.00, the share was 4.00% down and her money 19.99% down (derived). Paid in full with the same money, the close would have cost her 4.00%.
Then an up day, Thursday 29 October 2026. The same 52 shares at the open, ₹1005.00; at the close, ₹1045.80, the share was 4.06% up and her deposit 20.30% up (derived). The same five times, the other way.
Figure 4Leverage
Leverage cuts both ways
Friday 23 October 2026open ₹1003.10 → close ₹963.00 · low ₹941.00The share −6.19% from the open; her money −6.19%−4.00%
The share −6.19% from the open; her deposit −30.95%, −₹3229.20−19.99%−₹2085.20
Hatched: at the day's low, ₹941.00: the share −6.19%, her deposit −30.95% (−₹3229.20).
The same move on the share, five times the size on her deposit. At 5 times, a 20% fall on the share takes all of it.
Where it ends: at five times, a 20% fall in the share takes the whole deposit. A gap or a fast fall can take more than the deposit, and the rest is a debt owed to the broker. FINRA, the US brokers' regulator, makes every firm say it plainly: "You can lose more funds than you deposit". The same arithmetic holds in India.
A forced exit is not a safety net. If she does not close an intraday position herself, the broker closes it near the end of the day (placing your first order), at whatever price there is; on a day a share is locked at its limit there may be no buyer at all (circuit limits and surveillance).
Her loss budget sees it first. In risk management 101 she allowed ₹1000 to be lost on one trade. On 23 October the intraday position passed that well before the day's low, where it stood ₹3229.20 down. Leverage changes how far a fall travels before her stop, not where her stop is.
Intraday ends at the close. What if the app lends me money to keep the shares for weeks?
MTF: A Loan Tied to a Purchase
A regulated broker loan, with daily interest, secured by the shares it buys
"Pay a quarter, own the whole" sounds like a product, not a loan.
Read it as a loan: who lends, how much, at what rate, against what security.
And 0.04% a day is tiny, isn't it?
About 14.6% a year, charged whether the price rises, falls or stands still.
Who lends. In India a margin trading facility may be offered only by a corporate broker with a net worth of at least ₹3 crore and the exchange's approval, only on and equity ETFs (the most traded), and only with the client's written consent to its rights and obligations. SEBI, India's market regulator, proposed changes in June 2026 that were still under consultation on 30 October 2026.
How much. Maya's what-if, Friday 16 October (made up, on the real close): 37 shares at ₹1058.70 cost ₹39171.90. At 26.64%, the deposit needed is ₹10435.39; she puts in her ₹10587.00 and the broker lends ₹28584.90. That is 3.70 times her money; 38 shares would have needed ₹10717.43, more than she has (derived).
At what rate. 0.04% a day on the amount lent, from the day after purchase until the shares are sold: ₹11.43 a day on her loan, about ₹4173 over a year, 14.6% (derived). It is charged whether Lodha rises, falls or stands still. Rates and how days are counted are each broker's own; read yours.
Against what security: the shares themselves. The 37 shares arrive in her demat account pledged to the broker, in an account the rules call "Client Securities under Margin Funding Account", and the pledge must be released within one working day of her repaying.
. The same rate, 26.64% or whatever that day's is, applies to the lower of what she paid and what the shares are now worth, and any fall below her price comes off what counts as hers. Chapter 7 shows her week.
So is it the bank loan she refused? Partly. Both charge interest whatever happens, and both must be repaid. But the bank would have looked at her restaurant and her income and set monthly payments; the broker looks only at the share's price, every day, and can ask for more money within days, a margin call, or sell. In the US the same thing is a margin account: up to half the price borrowed at the start, and at least 25% of the value kept as equity (the value minus the loan) at all times, often 30 to 40% at firms.
Figure 5MTF
Two loans, one question
A margin loan on 37 Lodha sharesher what-if, Fri 16 Oct 2026And if I already own shares, can they be the deposit instead of cash?
Pledging and Haircuts
A lock on your shares, counted at less than their price
"Pledge" sounds like I hand my shares to the broker.
They never leave your demat account. A lock goes on them, in the broker's favour.
Then they count as money?
At less than their price, after a haircut. And they keep moving with the market.

Why a pledge, and not a handover: until 2020 many brokers took clients' shares into their own accounts for margin, and some misused them. In November 2019 Karvy Stock Broking was found to have pledged clients' shares to raise money for itself (SEBI and investor protection tells the case). Since SEBI's circular of 25 February 2020, in force from September 2020, a broker may take shares as margin only through a pledge in the depository.
The steps, on one line. In the app she picks the shares and the quantity to pledge. sends a one-time password to her registered mobile or email, and she confirms. A lock is marked on those shares in her own demat account, in favour of the broker, who may re-pledge them to the clearing corporation. The margin appears in her account, at their value less a haircut, explained next. To end it she unpledges, or sells, and the lock is released. The permission that lets a broker act for her is the DDPI from opening a demat and trading account.
counts each pledged share at less than its price, in case it falls before it can be sold. For Lodha the haircut equals its VaR margin, about 16% that week. It is not a charge and not a loss; it is the part that does not count.
A worked example (made up, on real files): if Maya owned 10 Lodha shares outright and pledged them, the file for 16 October valued them at ₹10618.00 and gave ₹8904.25 of margin. After Friday 23 October's close, the file for 26 October valued them at ₹9630.00 and gave ₹8076.68. Her margin fell ₹827.57 without a single trade (derived).
Figure 6Pledging
The shares stay; a lock goes on
 sent by the depository, CDSL
Figure 7Pledging
10 Lodha shares, pledged: what they count for as margin
What it is not: margin from pledged shares is not money she can withdraw, and a broker may value them at the lower of the last price and the previous close. If the haircut rises, the margin falls from the next day.
What stays the same: the shares are hers. Dividends, bonuses and splits arrive as usual. Pledging and unpledging carry a small charge at brokers, such as ₹15 plus GST per stock.
So if the shares I pledged fall on the same day my trade falls, I'm hit twice?
When Losses and Collateral Fall Together
When the security for a loan is the thing that falls, the fall hits twice
Is that only a beginner's problem?
It happens at every size: one account, a company's promoters, a whole fund.
And the selling makes the price fall further?
Often. A pledge invoked by a lender is a sale nobody in the market chose.
In one account: in Maya's MTF what-if, the 37 shares are both the purchase and the security for the loan. Every rupee Lodha falls takes ₹37 from her equity and lowers what the shares count for. The same is true when the shares you pledge and the shares you trade are alike, say two property developers: a bad day for one is often a bad day for both.
In a company's owners: Zee Entertainment, January 2019. Promoters, the founders or controlling owners, sometimes pledge their own shares to borrow. Zee's promoter group held about 41.6% of the company and had pledged about 59% of that. On Friday 25 January 2019, after a news report about the group, the share fell as low as ₹288.30 on NSE and , 26.61% below the day before (derived); the company's management said lenders selling pledged shares was part of the fall. Two days later the group said it had reached an understanding with its lenders. Invoking a pledge means the lender sells the pledged shares to get its money back, at whatever price the market offers that day.
Worldwide: Archegos, March 2021. A private investment firm in New York grew from about $1.5 billion to more than $36 billion, with about $160 billion of positions, about 4.4 times its money (derived), through loans and contracts from banks. When some of its biggest shares fell, it could not meet the margin calls; the banks sold, and their losses ran into billions of dollars, by the SEC's account. Its founder was later convicted of fraud and sentenced to 18 years: the leverage was legal, the lies to his lenders were not.
Figure 8Falling together
One loop, at three sizes
MayaDerived: 37 × (₹963.00 − ₹1058.70) = −₹3540.90 on her ₹10587.00.made up, on Lodha's real weekBorrowed against37 Lodha shares, ₹28584.90 lentWhat fell−33.45%of her money, as Lodha fell 9.04% in a weekWho soldher broker may, within 5 working days of a callWhere to check: NSE's pledged-data page and each quarter's shareholding pattern. Lodha's promoters held 70.29% on 30 Sep 2026 and had pledged none.: in India, promoters must report a pledge, its invocation or its release within seven working days, each quarter's shareholding pattern shows how many of their shares are pledged, and NSE lists them on its pledged-data page. On 30 September 2026 Lodha's promoters held 70.29% of the company and had pledged none. How to research a stock reads ownership as part of research; this is the line to check there.
Back to my 37 shares. On which day does the broker ask, and what can I do?
Shortfalls and Forced Exits
A shortfall is a bill with a deadline
Surely a margin call only comes after a big fall?
At the most the broker could lend you, a fall of 0.58% was enough.
Then I'd wait for the price to come back.
The loan sets the clock: at most five working days, maybe fewer. The deadline decides, not you.
(made up, on real closes and real rates): each evening the broker compares what she has that counts, the shares' value minus the loan, called her equity, with what is required, that day's rate on the lower of cost and value. On Friday 16 October she had ₹167.27 to spare.
Monday 19 October, Lodha ₹1030.00, 2.71% down on the day: equity ₹9525.10, required ₹10141.07, short ₹615.97. At the most the broker could lend, a fall of 0.58% was enough to bring a call (derived). Tuesday 20 October was a holiday on NSE.
Wednesday and Thursday, ₹1015.00 and then ₹1006.40: short ₹1012.02, then ₹1230.75.
Friday 23 October, ₹963.00, 4.31% down on the day: equity ₹7046.10, required ₹9488.54, short ₹2442.44. Her loss so far, ₹3540.90, is 33.45% of her money and three and a half times her loss budget of ₹1000; interest of about ₹57 is on top (derived).
Figure 9Shortfall
The week the cushion ran out
37 × ₹1058.70 = ₹39171.90
less the loan ₹28584.90 = equity ₹10587.00
required 26.60% × ₹39171.90 = ₹10419.73₹1058.70₹1058.70₹10587.00₹10419.73spare ₹167.27
37 × ₹1030.00 = ₹38110.00
less the loan ₹28584.90 = equity ₹9525.10
required 26.61% × ₹38110.00 = ₹10141.07₹1030.00₹1030.00₹9525.10₹10141.07short ₹615.97
37 × ₹1015.00 = ₹37555.00
less the loan ₹28584.90 = equity ₹8970.10
required 26.58% × ₹37555.00 = ₹9982.12₹1015.00₹1015.00₹8970.10₹9982.12short ₹1012.02
37 × ₹1006.40 = ₹37236.80
less the loan ₹28584.90 = equity ₹8651.90
required 26.54% × ₹37236.80 = ₹9882.65₹1006.40₹1006.40₹8651.90₹9882.65short ₹1230.75
37 × ₹963.00 = ₹35631.00
less the loan ₹28584.90 = equity ₹7046.10
required 26.63% × ₹35631.00 = ₹9488.54₹963.00₹963.00₹7046.10₹9488.54short ₹2442.44
: add cash to cover the shortfall; pledge other shares, if they count for enough after the haircut; or sell some of the 37 shares and repay part of the loan. Each costs something.
What the broker may do if she does not: under NSE's rules, sell the shares on the terms she agreed to, "not exceeding 5 working days from the day of margin call", and its own terms can be quicker. One broker's published terms say it "may square off", that is close the position, when the account goes negative. In the US the firm can sell without contacting you, and you are not entitled to more time. A sale is at the market's price that moment, not her price, and if it does not cover the loan, the rest is still her debt.
The week after: Lodha closed at ₹1045.80 on Thursday 29 October, 1.22% below her price (derived). Had she been sold on Friday, the loss would have been fixed near the week's low. Nobody knew that on Friday, and nobody knows it next time: the point is that the loan, not she, decided how long she could wait.
Figure 10Shortfall
The call's clock
Then what should I read before I ever switch this on?
Read the Obligation First
Five numbers to write before the offer is on the screen
Before switching on margin, MTF or a pledge, write five lines for your own trade. For Maya's what-if: what I would control, ₹39171.90 (37 shares); what I would owe, ₹28584.90 at 0.04% a day (₹11.43); the fall that brings a call, 0.58%, to ₹1052.54; the fall that takes all my money, 27.03%, to ₹772.56; who may sell, and by when: the broker, within 5 working days of a call, or sooner under its terms.
Figure 11The obligation
Five lines before you switch it on
Where to find each: the broker's MTF terms and its , which every client must be given; its risk policy; the margin shown on the order screen; and, in the US, the margin disclosure statement every firm must hand over. If a line cannot be filled from the written terms, that is your answer for now: not yet.
Maya's rule (hers, made up): "While I am learning, I trade only with money I have. If I ever use a loan, I will size it so that the fall that brings a call is bigger than my stop, and the loss at my stop is still ₹1000." Yours should fit your money and your nerves; what matters is that it is written before the offer is on the screen.
Her answer to her own question: yes, borrowing to trade is a loan, like the one she refused. It is quicker to take, quicker to call, and secured by the very shares it buys. Even on paper, she noticed she wanted to add money and wait for the bounce; trading psychology takes that feeling next.
Figure 12The obligation
The two falls on Lodha's price
The call sits ₹6.16 below her price; the end of her money, ₹286.14.
Before you go
Check yourself
4 questions from this lesson. Pick an answer to see why, then slide on to the next.
Question 1 of 4

Questions readers ask
Common questions
What is margin trading?
Buying with part of your own money and part borrowed from or carried by your broker, with your shares as security. Gains and losses are on the whole position; you pay interest on a loan; and if the price falls, you may be asked for more money or sold out.
Is margin trading the same as taking a loan?
Yes, in substance: a margin trading facility (MTF) is a broker's loan with daily interest, and intraday leverage is the broker carrying the rest until the close. Unlike a bank loan, it is judged on the share's price every day and can be called within days.
How much leverage can I get for intraday trading in India?
At most five times on shares: since 1 September 2021 brokers must collect at least 20% of the trade's value up front, or more when the clearing corporation's VaR plus ELM is higher. Brokers may offer less.
What happens if I don't meet a margin call?
The broker may sell your shares on the terms you agreed to; under NSE's MTF rules within five working days of the call, and sooner under its own terms. If the sale does not cover the loan, you still owe the rest.
Do I still get dividends on pledged shares?
Yes. Pledged shares stay in your demat account with a lock; you remain the owner, so dividends, bonuses and splits arrive as usual. You cannot sell them freely until the broker releases the pledge, which it does when you sell or unpledge.
What does it mean when promoters pledge their shares?
They have borrowed against them. If the price falls far enough, lenders can sell the pledged shares, adding to the fall. India requires promoters to disclose pledges within seven working days, and quarterly shareholding patterns show them.
Words to keep
The 24 words this lesson used, in plain English
Margin
Money or shares put down as a deposit against a position; it decides how big a position you may hold, not how much you can lose.