

Lesson 29
How to Read an Annual Report
Read a real annual report the way you would read your own books: pick the company or the group, follow your questions to the pages that answer them, and read what the notes and the auditor add.

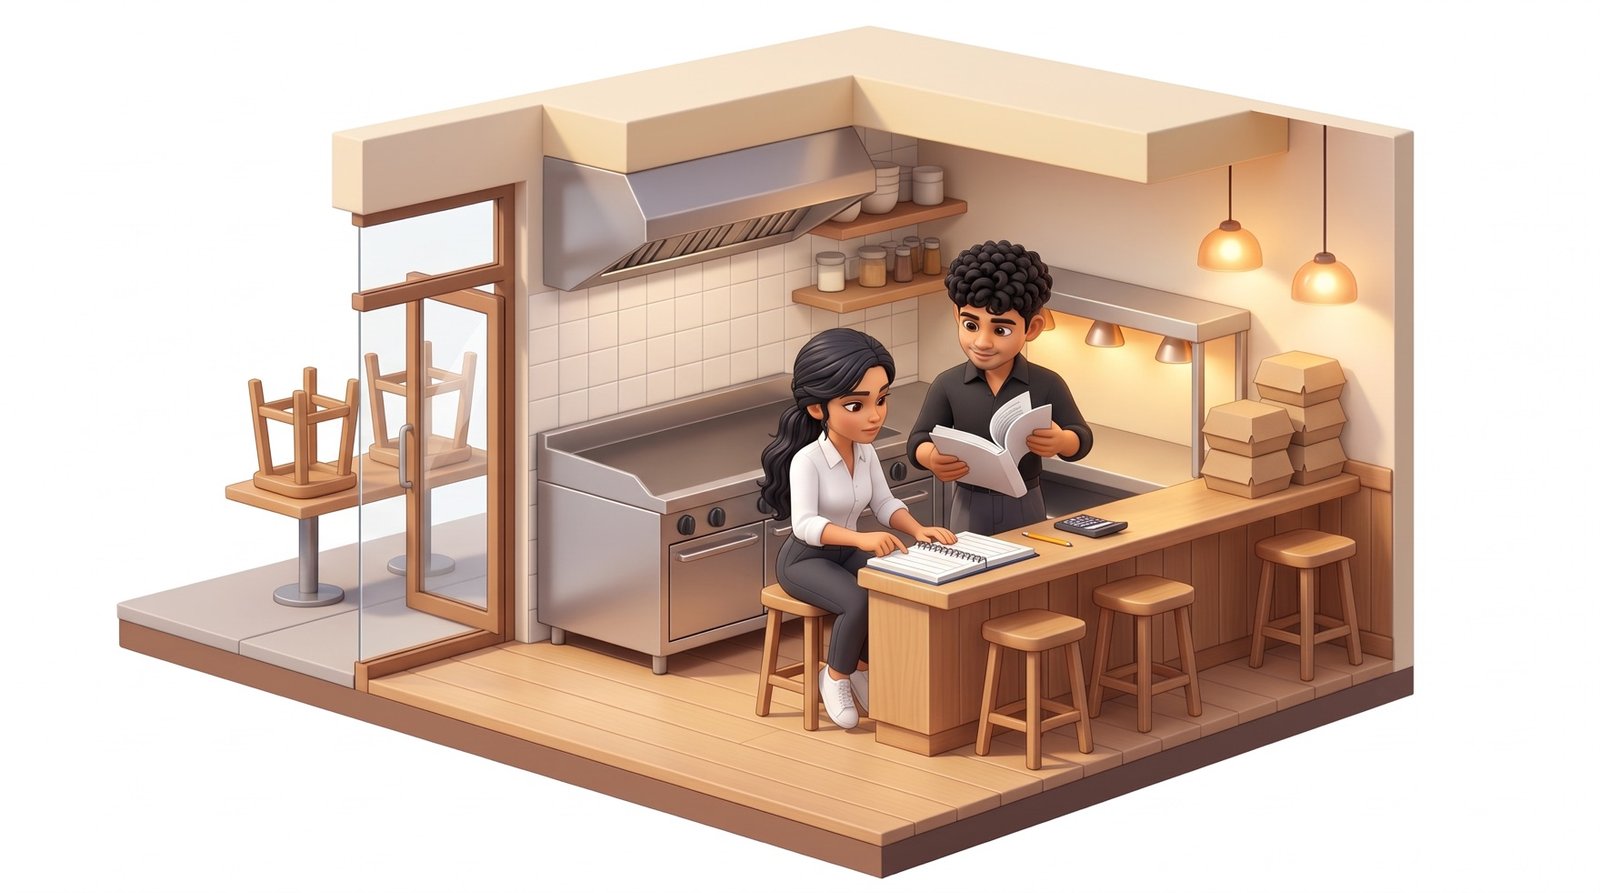
How to read an annual report for beginners: find the official filing, choose standalone or consolidated, and read it by question. The profit and loss shows what the year earned, the balance sheet what the company owns and owes, the cash flow where money really went, and the notes and the auditor's report how far to trust them.
On 29 May 2026 IndiGo, the airline, reported a loss of ₹2394 crore for the year to March. The same announcement said that, leaving out currency moves and one-off items, it made a profit of ₹7503 crore. Both numbers are true, for one year of flying 123.4 million passengers. Which one is the profit? The annual report lets you find out for yourself.
By the end you will be able to answer three questions: which report to read, and which set of accounts inside it; how to get from revenue to profit, and why profit is not cash; and what the notes and the auditor's report tell you that the totals do not.
Maya, who runs a burger restaurant and is learning to invest, and her books are made up. Mahindra & Mahindra, IndiGo (InterGlobe Aviation), Info Edge, Satyam and IL&FS are real, and every number about them comes from their own filings or official records, with the page. Amounts are in Indian rupees (₹): one lakh is 100000 and one crore is 10 million. India's financial year runs from April to March: FY26 is April 2025 to March 2026. Where we do our own arithmetic, the figure says "derived".
The Official Report: Standalone or Consolidated
Find the filed report, then choose the company alone or the whole group
Where it is. Start from the report the company itself filed, not a news story about it. A listed company files its annual report with the stock exchanges when it starts sending it to its shareholders, at least 21 days before its annual general meeting (AGM). On NSE, the National Stock Exchange of India, it sits in the company's corporate filings under "Annual Reports"; the company's own website has it under Investors. filed its report for FY26 with NSE on 4 July 2026. In the US the same yearly filing is the Form 10-K, free on the SEC's website.
Figure 1The report on the desk
Ask the report a question; it opens a real page
 Annual Report 2025-26p. 95
Board's report
₹ crore · standalone and consolidated
Both sets side by side: the company alone, and the group it controls.
Open Mahindra's filed report Annual Report 2025-26p. 243
Consolidated statement of profit and loss
₹ crore · consolidated
A loss, after a currency loss of almost ₹9000 crore.
Open IndiGo's filed reportAnnual Report 2025-26p. 296Note 31 · liquidity risk
₹ crore · lease payments, undiscounted
The leases' timetable: ₹14788 crore falls due within a year (derived).
Open IndiGo's filed report Annual Report 2025-26pp. 252-255
Standalone statements of profit and loss and of cash flows
₹ crore · standalone
Most of the profit was a rise in the value of shares it holds: no cash came in.
Open Info Edge's filed reportAnnual Report 2025-26p. 214Standalone note 33 · contingent liabilities
₹ crore · standalone
A possible debt, sized and explained, but not booked.
Open IndiGo's filed reportAnnual Report 2025-26p. 233Independent auditor's report
consolidated
Read the opinion first, then where the auditor looked hardest.
Open IndiGo's filed reportFigure 2Check first
Four things to check before you read a number
Check four things before you read a number: the company's exact name; the year (FY26 here); that it is the filed report, not an extract or a news summary; and the unit (Mahindra reports in ₹ crore).
Two sets of accounts. The standalone statements describe the listed company alone. The consolidated statements describe it together with the companies it controls, its subsidiaries, as one group. Mahindra & Mahindra Ltd itself makes SUVs, pickups and tractors. Its group adds Tech Mahindra, the lender Mahindra Finance, Mahindra Lifespaces, Club Mahindra and Mahindra Logistics.
The same year, two sizes. Income from operations was ₹147765 crore for the company alone and ₹198639 crore for the group, so the company is about three-quarters of the group (derived). Profit was ₹15639 crore for the company alone and ₹18622 crore for the group, of which ₹17099 crore belongs to Mahindra's own shareholders and ₹1523 crore to the other owners of its subsidiaries, called non-controlling interests. The biggest gap is debt: the company alone had borrowed ₹1056 crore, the group ₹129615 crore, about 120 times as much (derived), because the group includes a lender, Mahindra Finance, which borrows to lend. The group's loans to its customers came to ₹140317 crore.
Which to read. Neither is wrong. The consolidated set answers "what does a Mahindra share give me a part of?"; the standalone set answers "how is the car and tractor maker itself doing?". Headlines usually quote the consolidated figures. One trap: the company's own income from operations includes ₹2190 crore of income from its investments in its subsidiaries, associates and joint ventures (companies it owns in whole or in part), which the group's accounts do not count that way, because they already hold those companies' own results. Keep one scope for every comparison.
Figure 3Company or group
One company, two sizes
Mahindra & Mahindra Ltdthe company alone · standalonemakes SUVs, pickups and tractorspp. 313, 389about 120 times as much (derived)
p. 95the company is 74% of the group (derived)
pp. 95, 389-390the group's whole profit: ₹18622 crore, ₹1523 of it for other owners
The group includes Mahindra Finance, which borrows to lend: its loans to customers came to ₹140317 crore.
Nearly 500 pages. Where do I even start?
A Question-Led Route
Your own books' questions, and where a company's report answers them
Maya closes her restaurant's year with her accountant every April. This year, after the last order, she sets her own account book beside something new: the annual report of a listed company, nearly 500 pages long.

I keep my restaurant's books with my accountant. Can I read Mahindra's report the same way?
Mostly, yes. What do you ask of your own books each April?
What we earned, what we own and owe, and why the bank never matches the profit.
Those are the three statements. Theirs has more lines, and a group behind it.
So I start on page one and read to the end?
Start with your question. The contents page tells you where its answer lives.
Her year in three views, made up for this lesson. What the year earned, in the statement of profit and loss, which covers a period: sales of ₹36 lakh; food and packaging ₹13 lakh, wages ₹9 lakh, rent ₹4.8 lakh, gas, power and delivery-app fees ₹3.2 lakh, and ₹1 lakh for the wear on her griddle, fryer and scooter. That last cost is depreciation: the price of an asset spread over the years it is used. What is left: ₹5 lakh.
What she owns and owes on the last day, in the balance sheet, which is a photograph of one date: the griddle, the fryer, the scooter and the cash she owns; ₹1.5 lakh that an office caterer still owes her; the bills she owes her suppliers; and what is left for the two owners, called equity. What the restaurant owns always equals what it owes plus the owners' part.
Where the cash went, in the cash flow statement, again a period: ₹4.5 lakh came in from running the restaurant, which is the ₹5 lakh profit, plus the ₹1 lakh of depreciation that was never paid out in cash, less the ₹1.5 lakh not yet collected. ₹2 lakh went on a new fryer. ₹2 lakh was paid out to the owners, ₹20000 of it to the new buyer who owns 10%. Her bank balance rose ₹50000.
How they tie. The year's ₹5 lakh profit, less the ₹2 lakh paid out, raises the owners' part on the balance sheet by ₹3 lakh. The cash flow ends exactly at the balance sheet's cash. A listed company's statements tie the same way, with more lines; the notes behind them explain each line, and an auditor checks them.
Figure 4Maya's books
One year, three views
Made up for this lesson · Maya's restaurant · one year
- SalesIn a company's report
Revenue from operations₹36 lakh - Food, wages, rent, gas and feesIn a company's report
Expenses: materials, employee costs, rent, other expenses−₹30 lakh - Wear on the griddle, fryer and scooterIn a company's report
Depreciation−₹1 lakh
Left for the year₹5 lakh
- Griddle, fryer, scooterIn a company's report
Property, plant and equipment - The caterer still owes us ₹1.5 lakhIn a company's report
Trade receivables - Cash in the bankIn a company's report
Cash and cash equivalents - Bills we owe suppliersIn a company's report
Trade payables
Owners' part: change in the year+₹3 lakh
- From running the restaurantIn a company's report
Cash from operating activities: ₹5 lakh profit + ₹1 lakh depreciation − ₹1.5 lakh not yet collected+₹4.5 lakh - A new fryerIn a company's report
Cash used in investing activities−₹2 lakh - Paid out to the two ownersIn a company's report
Cash used in financing activities (₹20000 of it to the buyer who owns 10%)−₹2 lakh
Bank balance: change in the year+₹0.5 lakh
₹5 lakh earned− ₹2 lakh paid out to the owners+₹3 lakh owners' part
Cash flow ends at+₹0.5 lakh, the change in the bank on the balance sheet
Profit ₹5 lakh, but the bank rose only ₹0.5 lakh: the two are not the same number.
The route. Each of her questions has a home in a company's report. Is this the right company, year and scope? The cover, the Board's report and the heading of the auditor's report; Mahindra's Board's report sets both sets of figures side by side on page 95. How does it earn? The management discussion and analysis (MD&A) and the segment note: in Mahindra's FY26 report the statutory reports, with the MD&A, start on page 94, and note 44 runs from page 371 to 374. What did the year earn, and what does it own and owe? The statement of profit and loss and the balance sheet: pages 313 and 314 for the company alone, 389 and 390 for the group, with the notes on borrowings, leases and risks behind them. Did profit become cash? The cash flow statement, after each balance sheet. Can I trust the numbers? The notes, and the independent auditor's report: page 303 for the company alone, page 379 for the group.
Who owns it, and who runs it? The corporate governance report holds the shareholding table, the board and its committees, and the exchange has the latest quarterly shareholding pattern. In IndiGo's FY26 report, page 89 shows that its promoters, the group that controls the company, held 41.57% of its shares on 31 March 2026. This lesson finds and reads these answers; judging them is the work of how to research a stock.
Before the totals: what does Mahindra actually sell?
How the Business Earns Money
What it sells, and which part earns the profit
Two places tell you how a company earns: the MD&A, management's own account of the year, and the segment note, where the company reports each part of its business separately, with its sales and its segment result, roughly the profit that part made before interest and tax. The MD&A explains; the note gives numbers you can check its explanation against.
Mahindra's standalone accounts have two operating lanes (note 44). Automotive (SUVs, pickups and three-wheelers) had ₹109355 crore of income from operations and ₹10141 crore of segment result. (tractors) had ₹36409 crore of income and ₹7206 crore of result.
So tractors are a quarter of the two lanes' income but more than two-fifths of their result (derived: 25.0% and 41.5%). Each rupee of tractor sales left about 20 paise of result (a paisa is a hundredth of a rupee); each rupee of car sales, about 9 paise (derived: 19.8% and 9.3%).
Figure 5How it earns
A quarter of the sales, two-fifths of the profit
Notes to the standalone accounts · 44 Segment information₹ crore · FY26pp. 371-374 AutomotiveSUVs, pickups, three-wheelers
 Farm Equipmenttractors
Segment result is the company's own measure: profit before interest and tax, and before the corporate costs that no segment carries. It is not profit after tax, so the lanes do not add up to the bottom line.
Margins differ between lanes for reasons the note does not give: prices, costs, competition, new models. Read the MD&A for management's reasons and treat them as its view; whether a lane's margin is good is a question for how to research a stock.
Add every cost, and what is left at the bottom?
Revenue to Net Profit
IndiGo's year, line by line, and the figure the company prefers
IndiGo flew 123.4 million passengers and still made a loss?
A loss of ₹2394 crore. Now read the lines that moved it.
A foreign exchange loss of ₹8976 crore. That's more than its staff cost.
And the ₹7503 crore profit in its release is the company's own view, not the audited line.
The statement of profit and loss runs in a fixed order: revenue from operations (for an airline, ticket sales), other income (mostly interest on the cash it holds), the year's expenses, then exceptional items (large, unusual items shown on their own), tax, and the profit for the year. It ends with earnings per share (EPS): the profit divided by the average number of shares.
, for its group in FY26: revenue of ₹84962 crore and other income of ₹4552 crore, ₹89513 crore in all. Expenses: fuel ₹25389 crore; aircraft rentals and maintenance ₹14997 crore; staff ₹8272 crore; airport fees ₹6548 crore; depreciation ₹10808 crore; finance costs ₹5891 crore; other costs ₹8796 crore; and a of ₹8976 crore. Income less expenses: a loss of ₹164 crore (derived).
Then an exceptional item of ₹1796 crore, set aside for India's new labour codes, and tax of ₹433 crore: a loss of ₹2394 crore for the year, or −₹61.88 a share.
On the day of its results, IndiGo also gave another figure: a profit of ₹7503 crore "excluding the impact of foreign exchange and exceptional items". That is the company's own measure. It helps you see the flying business without the currency and the one-off, but it is not a line of the audited statement, and the currency loss is real money in rupees on debts IndiGo owes (chapter 5). Read both, and say which one you quote.
One-offs push both ways. Info Edge, which runs the jobs website Naukri.com, reported a FY26 profit of ₹5536 crore for the company alone, but ₹5200 crore of it came from a rise in the value of shares it holds (chapter 6). Its EPS was ₹85.49 after exceptional items and ₹17.04 before.
Figure 6Revenue to net profit
From ₹84962 crore of revenue to a ₹2394 crore loss
Consolidated statement of profit and loss₹ crore · year to 31 Mar 2026p. 243As filed: ₹849619 million+₹84962
As filed: ₹45515 million
mostly interest on its cash+₹4552
As filed: ₹253892 million−₹25389
As filed: ₹149968 million
rentals, supplementary rentals and maintenance: 20847 + 129121−₹14997
As filed: ₹108082 million−₹10808
As filed: ₹58908 million−₹5891
As filed: ₹236168 million
staff 82722 · airport fees 65482 · other 87964−₹23617
As filed: ₹89757 million
net; ₹1617.9 crore the year beforebooked as the rupee fell against the dollar−₹8976
As filed: ₹17964 million−₹1796
As filed: ₹4331 million−₹433
Figure 7One-offs push both ways
A gain on shares it holds lifted Info Edge's EPS from ₹17.04 to ₹85.49
Info EdgeFY26, the company aloneOne-offs push both ways: Info Edge's FY26 profit of ₹5536 crore included a ₹5200 crore gain on shares it holds; its EPS was ₹85.49 after exceptional items and ₹17.04 before.
Why would a weaker rupee cost an airline ₹8976 crore in one year?
What It Owns and Owes
IndiGo's balance sheet on 31 March 2026, drawn to scale
So the rupee fell and IndiGo booked a loss. What does it owe in dollars?
Almost all of its lease liabilities: ₹74975 crore of them are in US dollars.
And the owners' part is only ₹6987 crore?
About 5% of what it owns. That is book value, not what its shares are worth.
A balance sheet always balances: assets (what the company owns or controls) equal liabilities (what it owes) plus equity (what is left for its owners). It is a , here 31 March 2026.
IndiGo owned ₹136002 crore in all: ₹52054 crore of right-of-use assets (its right to fly the aircraft it leases), ₹11087 crore of aircraft and equipment it owns, ₹51674 crore of cash, bank deposits and investments, and ₹21187 crore of everything else (lines we grouped together).
It owed ₹75943 crore in lease liabilities: the payments still due on its leased aircraft, counted at today's value. Since April 2019, India's accounting rule for leases (Ind AS 116, which matches the international IFRS 16 of January 2019) puts almost every lease on the balance sheet, as an asset and a matching debt. Everything else it owed came to ₹53072 crore (derived), including ₹5931 crore of provisions and its bills to suppliers.
The owners' part was ₹6987 crore, about 5% of what it owns (derived). That is book value under the accounting rules, not what IndiGo's shares are worth on the market; market capitalisation is that other measure.
The answer to chapter 4. Note 31 shows that ₹74975 crore of the lease liabilities, 98.7% (derived), are owed in US dollars. When the rupee fell about 10% in the year, the same dollar debts cost more rupees, and the rise is booked as a loss. IndiGo's report says a 1% fall in the rupee against the dollar would cost it about ₹843 crore; ten such steps, roughly the year's fall, come to about ₹8430 crore (derived), close to the ₹8976 crore it booked. Its MD&A adds that these dollar liabilities are payable over eight to ten years: the loss is booked now, the payments come over years.
Figure 8What it owns and owes
What IndiGo owns, and what it owes
Consolidated balance sheet₹ crore · as at 31 Mar 2026p. 242₹52054.0 crore · 38.3%Aircraft and equipment it ownsOwn aircraft₹11087Property, plant and equipment
₹11087.1 crore · 8.2%Cash, deposits and investmentsCash and investments₹51674Cash, bank balances and investments (four lines)
₹51674.1 crore · 38.0%Everything elseEverything else₹21187All other assets, grouped by us
₹21186.9 crore · 15.6%
₹6987.4 crore · 5.1%Lease liabilitiesLease liabilitiespayments still due on leased aircraft₹75943₹74975 crore of it in US dollars (98.7%)Lease liabilities, non-current ₹64470.5 + current ₹11472.4 crore
₹75942.9 crore · 55.8%Everything else it owesEverything elseincl. ₹5931 crore of provisions and its bills to suppliers₹53072All other liabilities, grouped by us
₹53071.8 crore · 39.0%
Current items are due or used within about a year; non-current ones later. Chapter 7 reads the dates.
My profit was ₹5 lakh, but my bank rose only ₹50000. Does that happen to big companies too?
Profit Is Not Cash
Paid before it is earned, and a gain that brought in no money
Naukri's customers pay for a whole year upfront. Isn't all of that revenue?
Not yet. It is earned month by month, as Info Edge serves them.
And a ₹5200 crore gain brought in no cash at all?
Shares it holds rose in value. Profit on paper, not money in the bank.
Maya's ₹5 lakh profit became only ₹50000 more in the bank, because the office caterer had not paid, a fryer was bought and the owners were paid. A company's cash flow statement shows the same, in three parts: cash from operating activities (running the business), investing activities (buying or selling long-term assets and investments) and financing activities (borrowing, repaying and paying the owners).
Cash before revenue. runs Naukri.com. Employers pay upfront for a subscription, and the company counts the revenue evenly over the months it serves them. In FY26 it billed ₹3178 crore () and counted ₹3052 crore as revenue. On 31 March 2026, ₹1498 crore had been paid but not yet earned: it sits on the balance sheet as a liability, deferred revenue, because Info Edge still owes the service. Customers owed it only ₹10.8 crore.
Profit with no cash. The same year, Info Edge's own profit was ₹5536 crore, but its cash from operations was ₹1169 crore. The difference is mostly one entry: a ₹5200 crore rise in the value of the PB Fintech shares it received when a company it jointly owned merged into PB Fintech. The shares are worth more; no cash came in. The cash flow statement starts from profit before that gain and adds back what did not move money.
Figure 9Profit is not cash
Paid on day one, earned month by month
One employer pays ₹1.2 lakh on 1 January for a year of job listings (illustration)
Figure 10Paid first, earned later
Info Edge held ₹1498 crore of customers' money it had not yet earned
Info Edgeruns Naukri.com · FY26, the company alone · ₹ croreNeither gap is good or bad by itself. A gap between profit and cash is a question to follow into the notes; how much it should matter is a question for how to research a stock.
Figure 11Profit is not cash
Info Edge's profit of ₹5536 crore brought in ₹1169 crore of cash
Info EdgeFY26, the company aloneAnd money going out: when does a company have to pay back what it owes?
Debt: Cost and Due Dates
How much, how soon, at what cost, in which currency
IndiGo owes ₹75943 crore on its leases. Is that too much?
First ask when it is due. ₹14788 crore of payments fall within a year.
And it holds ₹51651 crore of cash, deposits and investments.
Part of it restricted. Set the near payments beside the cash at hand.
Four questions for any debt: how much, how soon, at what cost, and in which currency. The balance sheet gives the first; the notes give the rest.
How soon. IndiGo's note on lists its lease payments by date, before discounting: ₹14788 crore within a year, ₹49085 crore in one to five years and ₹25501 crore after five; ₹89374 crore in all. That is more than the ₹75943 crore on the balance sheet, because it includes the interest still to come.
Against what. The same page lists ₹51651 crore of cash, bank deposits and investments, of which ₹15434 crore is restricted (held as security), and ₹2606 crore of credit lines it had not drawn. IndiGo's own debt-to-equity measure (its debt divided by the owners' part), counting leases as debt, was 11.15 times. Whether that is high for an airline is a question for how to research a stock.
At what cost, and in which currency. Finance costs, the year's interest, were ₹5891 crore in FY26, against ₹5080 crore the year before; and chapter 5 showed the currency: US dollars.
When the dates come first: IL&FS. Infrastructure Leasing & Financial Services lent to and built roads and power projects that pay back over many years, and funded them partly with borrowing it had to keep rolling over, repaying old loans with new ones. In 2018 its group companies began missing payments; once its ratings fell, no one would refinance it. It owed more than ₹90000 crore. On 1 October 2018 the National Company Law Tribunal let the government replace its entire board. A total that had looked large but manageable became urgent because of the dates.
Figure 12Debt by due date
When IndiGo's lease payments fall due
Notes · 31 Financial instruments: liquidity risk₹ crore · undiscounted · 31 Mar 2026p. 296Before discounting, the payments add to ₹89374 crore; the balance sheet shows ₹75943 crore, their value today. Unused credit lines: ₹2606 crore.
Figure 13When the dates were missed
IL&FS, 2018: debts of more than ₹90000 crore it had to keep rolling over
The balance sheet gave me one line. Where did all these dates and dollars come from?
Follow the Notes
One line on the balance sheet, four notes behind it
What is this small number next to "Lease liabilities"?
Its note. Follow it, and the line tells you what it holds.
And a tax claim of ₹2418.5 crore that isn't on the balance sheet at all?
A contingent liability: disclosed with its reasons, not booked.
The small number beside a line on a statement is its note. In IndiGo's standalone balance sheet, the line "Lease liabilities" carries note 18.b, which says what the liability holds; note 31 gave chapter 5 its currency and chapter 7 its dates. The first notes, the accounting policies, say how each item is measured: leases, for example, at today's value of the payments still due.
What might still be owed. A provision is a liability already booked for a likely payment. A contingent liability is a possible one that depends on an outcome not yet known; it is disclosed in the notes, not booked. IndiGo's note 33, in its standalone accounts: if the tax authorities win their case that certain incentives it received on its aircraft are taxable, it would owe ₹2418.5 crore of income tax, before interest and penalty. Tax tribunals ruled for IndiGo; the department's appeals are pending in the Delhi High Court; on legal advice, no provision is booked. It is neither a debt nor nothing: a sized risk, with its reasons.
Who it deals with. A related party is a person or company closely tied to the company: its subsidiaries, its promoters, its directors and their firms. In IndiGo's standalone accounts, ₹32610 crore of its lease liabilities, about 39% (derived), are owed to related parties, mostly its own aircraft-leasing subsidiary in GIFT City, India's international financial services centre, which owned 78 aircraft on 31 March 2026 and leased 45 to IndiGo during the year. In the these leases disappear, because a group cannot owe itself (chapter 1). Most related-party dealings are ordinary business; the note lets you check who, what and at what price.
Figure 14Follow the notes
Follow one line into its notes
Standalone balance sheet · as at 31 March 2026Lease liabilities18.b₹83440 croreRead each note against last year's: a new policy, a new estimate or a re-sorted line can change a trend without anything changing in the business.
Who checks that any of these numbers are true?
The Auditor's Report
What the opinion promises, and what it does not
An auditor signed it. So the numbers must be right?
Not necessarily. An audit gives reasonable assurance, not certainty.
Then what do I read first?
The opinion: unmodified, qualified, adverse or a disclaimer. Then the key audit matters.

Where. Before each set of statements. IndiGo's auditor, S.R. Batliboi & Co LLP, signed its report on the group accounts on 29 May 2026 (page 233); Mahindra's, B S R & Co. LLP, signed on 5 May 2026 (page 303).
Read the opinion first. There are four kinds: unmodified (the statements give a true and fair view); qualified (they do, "except for" one material matter); adverse (they do not give a true and fair view); and a disclaimer (the auditor could not gather enough evidence to give an opinion). Every FY26 opinion read for this lesson is unmodified: IndiGo's on its group accounts, Mahindra's on both sets, and on its standalone accounts. Look also for a paragraph headed "Emphasis of Matter" or "Material Uncertainty Related to Going Concern": the auditor pointing at something you must read.
Then the : the areas that took most of the auditor's attention, with what was done about each. IndiGo's three: when passenger revenue is counted; the accounting and tax of aircraft leases and incentives; and provisions for aircraft maintenance. They are not separate opinions and not findings of wrongdoing; they tell you where the judgement is.
What it is not. An audit gives reasonable assurance on the financial statements: high confidence, not certainty. It does not prove every number right, it does not cover every claim in the glossy pages, and it says nothing about whether the share is worth buying.
When the cash was not there: Satyam. On 7 January 2009 the chairman of Satyam Computer Services wrote to his board that its balance sheet of 30 September 2008 showed ₹5361 crore of cash and bank balances, of which ₹5040 crore did not exist: about 94% (derived). That day its share closed at ₹40.25 on NSE, against ₹178.95 the day before (−77.5%, derived). The accounts had been audited. In 2011 the US SEC found that the auditors' staff, affiliates of PwC in India, had failed to confirm Satyam's cash balances; the affiliates agreed to pay $6 million and Satyam $10 million to settle. An audit lowers the risk of error and fraud; it cannot remove it.
Figure 15The auditor's report
Read the opinion first
The statements "give a true and fair view".a true and fair view
True and fair "except for" one material matter, which the auditor explains.true and fair, except for one matter
The statements do not give a true and fair view: the problem is material and pervasive.not a true and fair view
The auditor could not get enough evidence to give an opinion at all.no opinion given
S.R. Batliboi & Co LLPsigned 29 May 2026group accounts, p. 233 · 3 key audit mattersB S R & Co. LLPsigned 5 May 2026standalone p. 303, group p. 379S.R. Batliboi & Associates LLPsigned 22 May 2026standalone, p. 242What no report can tell you. It describes a finished year: the FY26 reports were filed months after 31 March 2026, and the business has moved on since. Later news comes in quarterly results and exchange filings. And reading the numbers is not yet judging them: turning them into a decision you can explain is the next lesson.
Figure 16When the report was false
Satyam's audited balance sheet showed cash that did not exist
Satyam Computer Services7 Jan 2009 · an audited balance sheet, 30 Sep 2008
The share on NSE that day: ₹178.95 → ₹40.25, −77.5%. In 2011 the US SEC found the auditors' staff had not confirmed the cash.
Before you go
Check yourself
4 questions from this lesson. Pick an answer to see why, then slide on to the next.
Question 1 of 4

Questions readers ask
Common questions
How do I read an annual report as a beginner?
Start from the report the company filed with the exchange, and check the company, the year and whether the figures are standalone or consolidated. Then read by question: the statement of profit and loss for what the year earned, the balance sheet for what it owns and owes, the cash flow for where money went, the notes for what each line holds, and the auditor's report for its opinion.
Should I read standalone or consolidated financial statements?
It depends on your question. Consolidated statements show the listed company and the companies it controls as one group; standalone shows the company alone. Use one scope for every comparison. At Mahindra in FY26, borrowings were ₹1056 crore standalone and ₹129615 crore for the group, which includes a lender.
Why can a company show a profit but little cash?
Profit follows the accounting rules; cash follows the money. Customers may not have paid yet, a gain may be on paper, or cash may have gone on new assets or on debt. Info Edge's FY26 standalone profit of ₹5536 crore included a ₹5200 crore paper gain; its cash from operations was ₹1169 crore.
What is a contingent liability in an annual report?
A possible obligation that depends on an outcome not yet known, such as a tax case. It is disclosed in the notes with its size and reasons, but not booked as a debt.
What does a qualified audit opinion mean?
The auditor says the statements give a true and fair view except for one material matter, which it explains. An unmodified opinion has no such exception; an adverse opinion says the statements are not fairly presented; a disclaimer means the auditor could not form an opinion.
Where can I find a company's annual report?
On the stock exchange's website under the company's filings (NSE and BSE list them under annual reports) and on the company's own investor page. In the US, the yearly Form 10-K is on the SEC's website.
Words to keep
The 16 words this lesson used, in plain English
Annual report
A listed company's yearly report: the Board's report, the management discussion and analysis, governance, and the audited financial statements with their notes. Mahindra filed its FY26 report with NSE on 4 Jul 2026.