

Lesson 11
Mutual Fund vs Index Fund vs ETF, Explained
A mutual fund pools many people's money into one set of investments; an index fund copies a list such as the Nifty 50 for less; an ETF is that copy sold on the stock exchange. What a unit and its NAV are, what each costs, SIP or lump sum, how to read a factsheet, and what no fund protects you from.

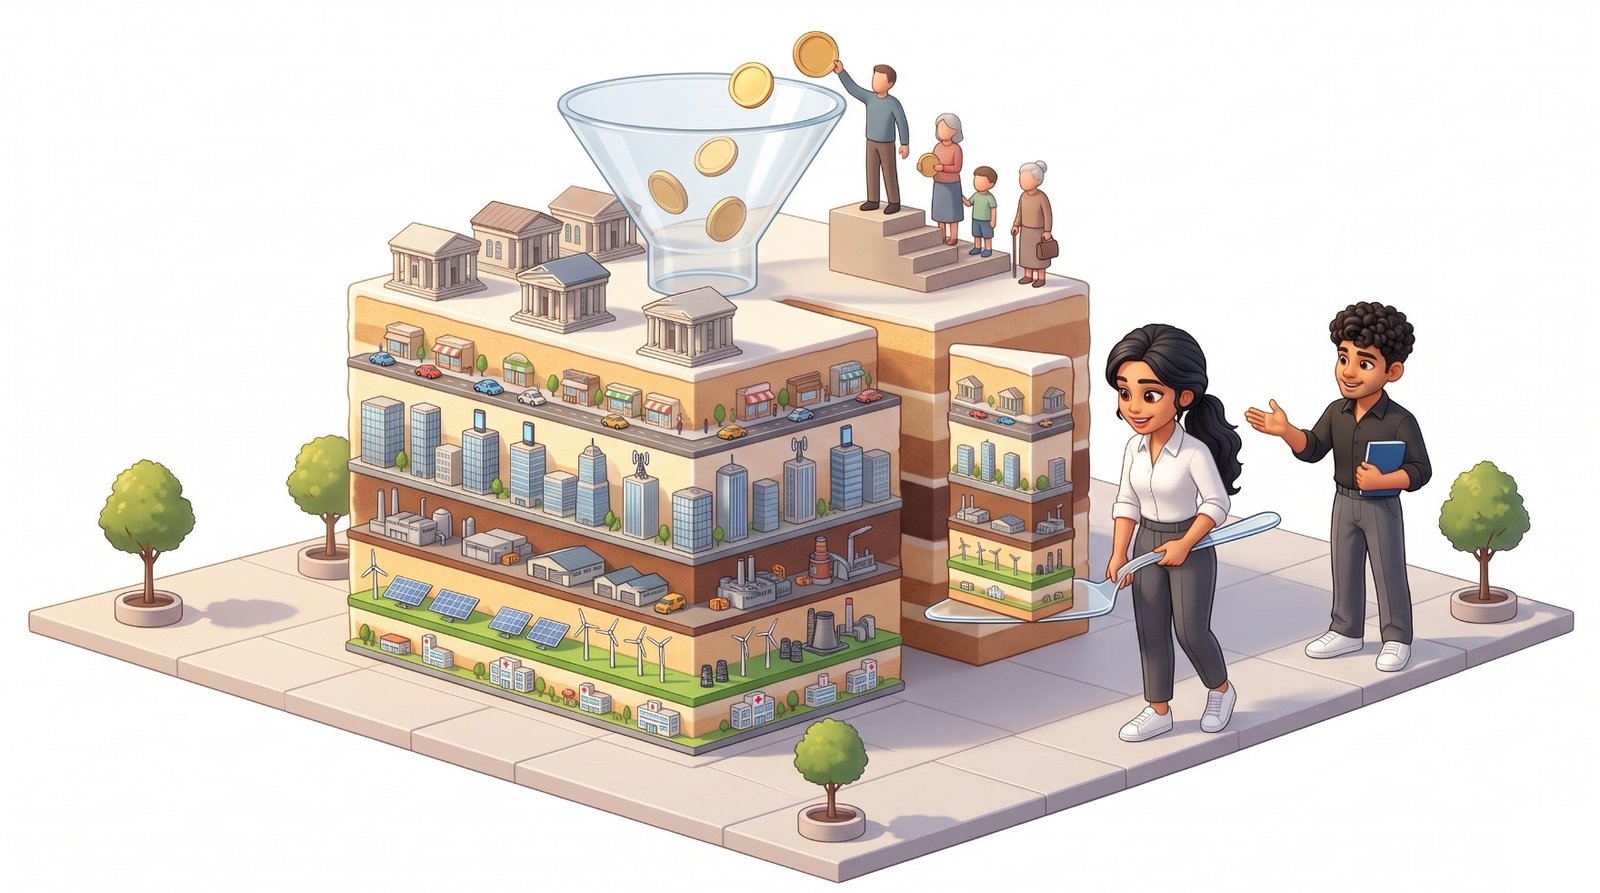
Mutual fund vs index fund vs ETF: all three pool many people's money into many investments. A mutual fund is the pool. An index fund is a mutual fund that copies an index instead of picking shares. An ETF is a fund too, usually an index copy, traded on a stock exchange at prices that move through the trading day.
On 31 August 1976, the first index fund for ordinary investors opened in the United States with about $11.3 million, far less than its founder, John Bogle, had hoped. Critics called it "Bogle's folly". By the end of 2023, index funds and ETFs held more of America's fund money than actively managed funds, for the first time. How did a fund that only copies a list win so much of that money, and what does it mean for someone who runs a kitchen, not a research desk?
By the end you will be able to answer four questions: what you own when you buy a unit of a fund, and what its NAV tells you; the real difference between an index fund and an ETF, and what each costs you; whether money should go in all at once or a little each month; and what no fund can protect you from.
This lesson follows Maya, who runs a burger restaurant and is learning to invest, with Mr. Chartist as her guide. Maya and her amounts are made up, and so is the sample fund in chapter 7; every company, fund event, price and date beside her is real and dated, and no fund in this lesson is named as a choice. Amounts are in Indian rupees (₹): one lakh is 100000 and one crore is 10 million. India's rules are named as India's, with a line on the US where it differs. The last lesson showed a fund as one basket on the shelf; this one opens the basket.
What a Fund Is
One pool, many owners

One company's annual report took my whole afternoon. How would I ever own fifty?
Pool your money with many others. A fund buys all fifty, and you own a slice.
So the fund house keeps my money, like a bank deposit?
No. It runs the money for a fee. The fund belongs to its investors.

A collects money from many people into one pool and invests it by a plan written down before the first rupee arrives: "own large Indian companies", say, or "copy a list of fifty". Each investor owns a part of the whole pool in proportion to the units they hold (chapter 2). What the pool holds decides what you own: shares (equity funds), loans to governments and companies (debt funds), or both (hybrid funds). This lesson mostly uses a fund of shares.
An index is a list of companies with fixed rules for how much of each it counts. The Nifty 50 is a list of 50 large Indian companies kept by NSE's index company; the S&P 500, 500 large US companies, plays the same part in the US. Market indices explains how one is built.
Here is one ₹1000 two ways, at the closing prices of Friday 23 October 2026. On her own, at Tata Steel's NSE close of ₹167.67, ₹1000 buys five whole shares: ₹838.35 of one steelmaker, with ₹161.65 left over. In a fund that copies the Nifty 50, the whole ₹1000 is spread over all 50 by the index's weights at the same close (less 5 paise of stamp duty, India's tax of 0.005% on units bought from the fund itself, left out of these sums): ₹101.55 of HDFC Bank, ₹95.57 of ICICI Bank, ₹76.08 of Reliance and so on, down to ₹5.29 of the smallest; the ten largest take ₹534. Tata Steel is on the list too, and its part is ₹13.30. On her own, ₹838.35 rides on one company; in the fund, ₹13.30 does.
Figure 1What a fund is
One ₹1000, two ways, at the same close
On your own5 whole shares of one company, at ₹167.67
Through a fund that copies the Nifty 50a slice of all 50 at the same close · who holds it?Who holds the money
The fund house decides what to buy and sell, inside the written plan, for a yearly fee. Trustees hold everything in trust for the unit holders; a custodian, a separate firm, keeps the securities. The lock stops theft. It does not stop a falling market (chapter 8).
 ₹167.671 share₹167.671 share₹167.671 share₹167.671 share₹167.671 share
 ₹101.55HDFC Bank
₹101.55 of the ₹1000, 10.16% of the index
 ₹95.57ICICI Bank
₹95.57 of the ₹1000, 9.56% of the index
 ₹76.08Reliance
₹76.08 of the ₹1000, 7.61% of the index
 ₹55.02Bharti Airtel
₹55.02 of the ₹1000, 5.50% of the index
 ₹40.82L&T
₹40.82 of the ₹1000, 4.08% of the index
 ₹38.97Infosys
₹38.97 of the ₹1000, 3.90% of the index
 ₹37.88SBI
₹37.88 of the ₹1000, 3.79% of the index
 ₹33.47Axis Bank
₹33.47 of the ₹1000, 3.35% of the index
 ₹30.31Kotak Bank
₹30.31 of the ₹1000, 3.03% of the index
₹24.70 of the ₹1000, 2.47% of the index
₹24.44 of the ₹1000, 2.44% of the index
₹24.24 of the ₹1000, 2.42% of the index
₹23.77 of the ₹1000, 2.38% of the index
₹21.99 of the ₹1000, 2.20% of the index
₹17.70 of the ₹1000, 1.77% of the index
₹16.99 of the ₹1000, 1.70% of the index
₹15.40 of the ₹1000, 1.54% of the index
₹14.33 of the ₹1000, 1.43% of the index
₹13.96 of the ₹1000, 1.40% of the index
₹13.54 of the ₹1000, 1.35% of the index
Tata Steel₹13.30 of the ₹1000, 1.33% of the index
₹12.76 of the ₹1000, 1.28% of the index
₹12.62 of the ₹1000, 1.26% of the index
₹12.51 of the ₹1000, 1.25% of the index
₹12.40 of the ₹1000, 1.24% of the index
₹12.04 of the ₹1000, 1.20% of the index
₹11.59 of the ₹1000, 1.16% of the index
₹10.91 of the ₹1000, 1.09% of the index
₹10.87 of the ₹1000, 1.09% of the index
₹10.71 of the ₹1000, 1.07% of the index
₹10.51 of the ₹1000, 1.05% of the index
₹10.44 of the ₹1000, 1.04% of the index
₹9.97 of the ₹1000, 1.00% of the index
₹9.85 of the ₹1000, 0.98% of the index
₹9.32 of the ₹1000, 0.93% of the index
₹9.20 of the ₹1000, 0.92% of the index
₹9.10 of the ₹1000, 0.91% of the index
₹8.68 of the ₹1000, 0.87% of the index
₹8.45 of the ₹1000, 0.84% of the index
₹8.06 of the ₹1000, 0.81% of the index
₹8.03 of the ₹1000, 0.80% of the index
₹7.61 of the ₹1000, 0.76% of the index
₹7.20 of the ₹1000, 0.72% of the index
₹7.17 of the ₹1000, 0.72% of the index
₹7.05 of the ₹1000, 0.70% of the index
₹6.43 of the ₹1000, 0.64% of the index
₹6.00 of the ₹1000, 0.60% of the index
₹5.80 of the ₹1000, 0.58% of the index
₹5.39 of the ₹1000, 0.54% of the index
₹5.29 of the ₹1000, 0.53% of the index
Tata Steel₹13.30The other 39₹452.33Tata Steel: ₹13.30The other 39 together: ₹452.33 of the ₹1000
₹101.55HDFC Bank₹101.55 of the ₹1000, 10.16% of the index
₹95.57ICICI Bank₹95.57 of the ₹1000, 9.56% of the index
₹76.08Reliance₹76.08 of the ₹1000, 7.61% of the index
₹55.02Bharti Airtel₹55.02 of the ₹1000, 5.50% of the index
₹40.82L&T₹40.82 of the ₹1000, 4.08% of the index
₹38.97Infosys₹38.97 of the ₹1000, 3.90% of the index
₹37.88SBI₹37.88 of the ₹1000, 3.79% of the index
₹33.47Axis Bank₹33.47 of the ₹1000, 3.35% of the index
₹30.31Kotak Bank₹30.31 of the ₹1000, 3.03% of the index
₹24.70 of the ₹1000, 2.47% of the index
Apollo Hospitals: ₹7730 a share, but 0.761% of the index. One share at that weight needs ₹7730 ÷ 0.761% = ₹1016199 in all (derived).
Why not buy all fifty herself? Whole shares make it costly. To hold all fifty in the index's own proportions, the share that is dearest for its small weight sets the minimum: Apollo Hospitals closed at ₹7730 that Friday but was only 0.761% of the index. If one ₹7730 share is to be only 0.761% of your portfolio, the portfolio must be ₹7730 ÷ 0.761%: just over ₹10 lakh, more than all the savings Maya can reach, and the other 49 would still round to whole shares. A fund does it with ₹1000 because it pools many investors' money and cuts the pool into units that come in fractions.
Who does what, in Maya's terms. The (an asset management company, or AMC) is the cook: it decides, inside the written plan, what to buy and sell, and is paid a yearly fee. The pantry is not the cook's. In India the money and the shares are held by trustees "in trust for the benefit of the unit holders" and kept by a custodian, a separate firm that holds the securities; SEBI registers every fund in India, as the SEC does in the US. The comparison stops here: the lock on the pantry stops the cook walking off with the food. It does not stop a bad recipe or a falling market (chapter 8).
So my ₹1000 is spread over fifty companies. What do I actually hold?
NAV and Units
What one slice is worth tonight

One fund's unit is ₹10 and another's is ₹100. The ₹10 one is cheaper, so I get more for my money?
You get more units, not more fund. Cut a burger into four or into eight: is an eighth a cheaper burger?
No, just a smaller piece of the same burger.
Units work the same way. The NAV is one slice's value at tonight's close, nothing more.
So if both funds hold the same companies and rise 10%, my ₹10000 grows the same in each?
To the rupee. A low NAV often means a young fund, or one that has fallen. Neither makes it cheap.
When Maya's money goes in, the fund does not hand her HDFC Bank shares. It issues units: equal slices of everything it holds, so every unit carries the same mix as the whole fund.
NAV (net asset value) is one unit's value: everything the fund owns at the day's closing prices, minus what it owes, divided by the number of units. In India it must be worked out every business day and, for most funds, published by 11 pm on 's and the fund's own websites; funds of funds and funds investing abroad publish the next morning.
The low-NAV myth in numbers: stamp duty takes 50 paise first, so ₹10000 at a NAV of ₹10 buys 999.950 units, and at a NAV of ₹100 it buys 99.995. After the same 10% rise, both are worth ₹10999.45. What decides your gain is how far the fund's holdings rise, never the price of one unit.
Figure 2NAV and units
Every unit is a slice of the whole fund
The white line: Tata Steel, 1.33 of the 14.31 industry points, in the fund and in every unit
₹6822 crore of net assets÷99.71 crore units=₹68.42 a unitthe NAV · an illustration
The same money, the same growth, any NAV
NAV₹10
₹10000 buys999.950 units
after the same +10%₹10999.45
Both end at the same value.NAV₹100
₹10000 buys99.995 units
after the same +10%₹10999.45
More units of a smaller slice, or fewer of a bigger one: the same fund either way.
A worked purchase, as an illustration: ₹5000 at a NAV of ₹68.42. Stamp duty of 0.005% takes ₹0.25, and ₹4999.75 ÷ ₹68.42 gives 73.074 units. Units come in fractions, so all of the money is invested.
Which day's NAV an order gets, in India: for most funds, money that reaches the fund by 3 pm gets that day's NAV, and later money gets the next business day's. Liquid and overnight funds, which lend for one day up to about three months, have an earlier cut-off, 1:30 pm. The US works the same way: in the SEC's words, you will not know the exact price until the end of the business day.
Unlike a share's price, the NAV of an fund does not rise because many people buy it. New money gets new units at the day's NAV, and the number of units grows. Only an ETF's price on the exchange can be pushed above its value by buyers (chapter 4).
Someone decides what goes into the pool. Who, and how?
Active and Passive
Pick the companies, or copy the list
Surely paying an expert to pick the shares gets me a better result?
It buys a chance. Over ten years, 74 of every 100 active large-cap funds in India trailed the index they aim to beat.
Then copying the list always wins?
Not always: in 2025 most mid- and small-cap funds beat theirs. But copying always costs less.
A benchmark is the index a fund is measured against, named in its documents. An active fund pays a manager and analysts to choose what to hold, trying to do better than that benchmark. A passive fund, an index fund or an ETF, follows an index's list and weights instead; in India it must keep at least 95% of its assets in the index's securities.
Picking costs more. In India the base yearly cost of an active equity fund may be up to 2.10% of its assets on its first ₹500 crore, falling as the fund grows; an index fund's or ETF's may not exceed 0.90%. On ₹1 lakh, that is up to ₹2100 a year for an active equity fund while its own assets are under ₹500 crore, and up to ₹900 for an index fund or ETF, both before levies and trading costs. Each factsheet shows the actual figure (chapter 7).
A passive fund trails its index slightly, by its costs and small timing gaps. The wobble of that gap is its tracking error, which in India may not exceed 2% a year.
The record, from S&P's SPIVA India scorecard: of India's active large-cap funds (funds that buy the biggest listed companies; market cap and stock categories explains size), 85% trailed their benchmark in the first half of 2026, 80% over three years, 85% over five and 74% over ten. The benchmark is S&P's own India LargeMidCap index, which also includes mid-sized companies. Over ten years the share behind was above 70% in every category S&P reports, and 82% for mid- and small-cap funds.
Figure 3Active and passive
Seventy-four of every hundred, over ten years
January to June 2026: the S&P India LargeMidCap fell 4.0%, the average active large-cap fund 5.1%.85of 100 behind15 ahead
Three years to 30 Jun 2026.80of 100 behind20 ahead
Five years to 30 Jun 2026.85of 100 behind15 ahead
Ten years to 30 Jun 2026. Over ten years the share behind was above 70% in every category S&P reports; 82% for mid- and small-cap funds.74of 100 behind26 ahead
Some years go the other wayMid- and small-cap funds
2025: only 12 of 100 behind a benchmark that fell 7.9%, their best year against it since 2014; the average fund still lost 0.7%. The next six months, to June 2026: 67 of 100 behind.: in 2025 most mid- and small-cap funds beat a falling benchmark.
Some years go the other way. In 2025, when their benchmark fell 7.9%, only 12.1% of active mid- and small-cap funds trailed it, their best year against it since 2014, though the average fund still lost 0.7%: beating a falling index can mean losing less. In the first half of 2026, 67% trailed again. In the US, 79% of active large-cap funds trailed the S&P 500 in 2025, and 67% in the first half of 2026.
What this means: an active fund buys a chance to beat the index; a passive fund buys the index's result minus a small cost. That is much of how Bogle's "folly" won: over long periods most pickers trailed the list they were measured against, and the list costs less. Neither kind removes the market's falls (chapter 8).
If a copy of the index is enough for me, where do I buy the copy?
Index Funds and ETFs
One basket, two doors
An index fund and an ETF. Are they two different investments?
They can hold the very same basket. Only the door you buy through differs.
And an ETF's price, isn't that simply its value?
Usually close. In October 2025 buyers paid about 3% above a silver ETF's value.
An index fund and an ETF (exchange-traded fund) that track the same index hold the same companies in the same weights. What differs is the door you buy through.
Door one, the fund house. You buy units from the fund and sell them back to it at the day's NAV, any amount from its minimum up, in fractions, and by SIP if you like; in India no demat account is needed. After a sale, India's rule is that the money reaches your bank within three working days for most funds (chapter 8 shows a case where it did not).
Door two, the exchange. An ETF's units must be listed and traded on a stock exchange. You buy whole units from another investor through a broker, into a demat account (the three accounts), during market hours (market timings), at the market price, paying the broker's and the exchange's charges (brokerage and charges) and the gap between buyers' and sellers' prices.
Figure 4Index funds and ETFs
One basket, two doors
 Index fundthe fund house's door
 ETFthe exchange's door
₹5000 at a NAV of ₹68.42 buys 73.074 units, after ₹0.25 of stamp duty (chapter 2).The market price, in whole units; it can drift from the iNAViNAV
The basket's value worked out through the trading day and shown on the exchange. Compare the price with it before an order.
Mutual fund vs index fund vs ETF, side by side: an active fund and an index fund are both bought from the fund house at the day's NAV, both come as a direct and a regular plan (chapter 5), both take a SIP, and both charge stamp duty and any exit load (a fee some funds charge for selling early). In India an active equity fund's base yearly cost is capped at 2.10% on its first ₹500 crore, falling with size to 0.95%; an index fund's and an ETF's at 0.90%, before levies and trading costs. An ETF has one plan, bought through a broker; it takes no SIP from the fund house, since each purchase is an order on the exchange; its money comes back through the exchange's settlement; and it is the only one of the three whose price can differ from its value.
The idea is fifty years old. From Bogle's index fund of 1976 it moved to the exchange: the world's first ETF began trading in Toronto on 9 March 1990, the first US one in January 1993, and India's first, Nifty BeES, on NSE on 8 January 2002. By September 2026 India's index funds and ETFs held ₹14.70 lakh crore, 17.8% of all the money in its mutual funds.
Why an ETF's price usually stays near its value: large firms called market makers (the rules call them authorised participants; every Indian ETF has at least two) can create new units from the fund house by handing over the basket, or hand units back for it, when price and value drift apart (who market makers are). The iNAV (indicative NAV) is the basket's value worked out through the trading day and shown on the exchange. In the SEC's words, an ETF's market price "generally stays close" to its end-of-day NAV, though "it may vary significantly".
The clearest recent gap came in silver; ETFs can hold gold or silver instead of shares. On Thursday 9 October 2025, Nippon India's silver ETF closed at ₹156.16 on NSE, ₹4.58 (about 3%) above that day's NAV of ₹151.58. During the day the gap was wider: Business Standard reported the ETF at 5.5% over its iNAV, and three other silver ETFs at 10% or more. Every new unit had to be backed by physical silver, which was short in India: "the current limited availability of physical silver has constrained the creation of new units," SBI Mutual Fund said. Kotak stopped new lump-sum money into its silver fund-of-funds (a fund that buys the ETF's units for investors without a demat account) from 10 October, and Tata, UTI and SBI paused theirs too.
By Friday 17 October the gap had turned round: the same ETF closed at ₹160.60, below that day's NAV of ₹163.37. Over those six sessions the silver behind each unit rose about 8%. How far ahead was a buyer at the 9 October close? Only about 3%: they paid ₹156.16 and could sell at ₹160.60. The premium paid had gone.
What to take from it: before any ETF order, compare the price with the iNAV, published through the trading day; a limit order caps the price you pay (placing your first order). ETFs usually trade close to their value; this gap opened because the thing inside was hard to get.
Figure 5A real case
The silver rose 8%. The buyer at the premium made 3%.
 Nippon India Silver ETF6 sessions, 9 to 17 Oct 2025
Every new unit had to be backed by physical silver, and silver was short in India, so new units could not be made fast enough. Kotak stopped new lump-sum money into its silver fund-of-funds from 10 October; Tata, UTI and SBI paused theirs too.17 Oct 2025six sessions laterFri 17 Oct 2025
The close was below that day's NAV: the premium paid on 9 October had gone.
The premium paid had gone. Before an ETF order, compare its price with the iNAV.
Nobody has sent me a bill for any of this. What am I paying?
Expense Ratio, Direct and Regular Plans, Exit Load
The costs that never arrive as a bill
My fund statement shows no fees at all. Is it free?
The cost is taken from the fund every day, so it shows only as a lower NAV.
But 1% a year sounds tiny.
One point a year more leaves you about 18% less after twenty years.
The expense ratio is a fund's yearly running cost as a share of your money. It is taken a little every day from the fund's assets, so it shows as a slightly lower NAV, never as a bill. In India, from 1 April 2026, it has a capped base part (the fund house's fee, distribution, the registrar, custody and other running costs) with taxes, levies and trading costs on top; the factsheet shows the total for each plan.
In rupees: 0.20% a year on ₹1 lakh is about ₹200 in the first year; 1.20% is about ₹1200.
Why the difference grows: the cost is a share of the whole pot every year, including what earlier years added, and the money it takes stops growing too (compounding). A yearly cost one percentage point higher leaves you with about 18% less after 20 years, whether the market grows fast or slowly. The SEC's own example: $100000 growing 4% a year for 20 years ends at about $208000 with a 0.25% yearly fee and $179000 with 1%. Slide the years in the figure below and watch the gap grow.
Direct and regular plans, in India: every fund you buy from a fund house offers two plans of one portfolio. A regular plan is bought through a distributor, who is paid a commission out of the fund's expenses; a direct plan, required since 1 January 2013, is bought without a distributor (from the fund house, or a platform that takes no commission) and pays none. Same holdings, a lower expense ratio, two NAVs: the direct plan's grows a little faster. A distributor may give help and service, which is what the commission pays for; whether it is worth it is your call (check whom you pay). An ETF, bought on the exchange, has one plan. In the US the same idea appears as share classes: some carry a sales charge, a "load", that pays the seller; others do not.
Figure 6Costs
What one point a year takes
After 20 years, on ₹1 lakh
18.3% lessto end with, at one point a year more
costing 0.5% a year₹198211
costing 1.5% a year₹161954
what the extra point took₹36257
After 20 years: ₹198211 at 0.5% a year, ₹161954 at 1.5%; the extra point took ₹36257, 18.3% lessFigure 7Costs
The same fund, two plans
 Direct planNo commissionits own NAV · the lower expense ratio, so its NAV grows a little fasterRegular planThe distributor's commission is paid inside the expense ratioits own NAV
An exit load is a fee some funds charge if you sell within a stated time. It is in the scheme's documents and on the factsheet, it goes back into the fund for the investors who stay, and in India it may not exceed 3% of the NAV. As an illustration: with a 1% exit load for sales within 12 months, selling ₹50000 in month 8 leaves ₹500 in the fund; in month 13 it costs nothing. Indian funds have charged no entry fee since 2009.
Other costs, one line each: stamp duty on purchases (chapter 2); brokerage and exchange charges on ETFs, and tax on gains when you sell (brokerage, charges and taxes).
My savings are already here, and the restaurant adds more each month. All at once, or bit by bit?
SIP and Lump Sum
All at once, or a little each month
At closing time on the last day of the month, Maya totals what the restaurant has left after rent, wages and suppliers. Her savings already hold a sum meant for a home about ten years away; this new money will keep arriving every month, and she wants to know how each should go in.
Everyone asks me: SIP or mutual fund? Which should I pick?
A SIP is a way of buying a fund: the same fund, paid in month by month.
And does buying monthly protect me from falls?
No. In 2008 it lost less than all at once, but it still lost.
A SIP () sends a fixed amount from your bank account into a fund on a set date, usually each month, under a standing . Each instalment buys units at that day's NAV: more units when the NAV is low, fewer when it is high. In the US the same habit is called dollar-cost averaging, equal amounts at regular intervals whatever the market does; a 401(k) plan that invests part of each paycheck works the same way. A lump sum is money you already have, put in at once. Maya has both kinds: say ₹1.2 lakh already in hand, and ₹10000 arriving each month.
Two real years, on the Nifty 50's own closes (the price index, so no dividends or costs; an illustration). In 2008, ₹1.2 lakh put in at once on 1 January was worth ₹59244 on 1 January 2009; ₹10000 on the first trading day of each month was worth ₹85953. In 2023, at once became ₹143373 by 1 January 2024, and monthly ₹139753. In 2008 each later instalment bought more units as prices fell; in 2023 the money put in at once had more months in a rising market.
Figure 8SIP and lump sum
Two real years, two winners
2008a falling year: buying monthly lost less
Nifty 50 6144.35 · ₹10000 bought 1.628 units
Nifty 50 5317.25 · ₹10000 bought 1.881 units
Nifty 50 4953.00 · ₹10000 bought 2.019 units
Nifty 50 4739.55 · ₹10000 bought 2.110 units
Nifty 50 5228.20 · ₹10000 bought 1.913 units
Nifty 50 4739.60 · ₹10000 bought 2.110 units
Nifty 50 3896.75 · ₹10000 bought 2.566 units
Nifty 50 4413.55 · ₹10000 bought 2.266 units
Nifty 50 4348.65 · ₹10000 bought 2.300 units
Nifty 50 3950.75 · ₹10000 bought 2.531 units
Nifty 50 3043.85 · ₹10000 bought 3.285 units
Nifty 50 2682.90 · ₹10000 bought 3.727 units
2023a rising year: all at once ended ahead
Nifty 50 18197.45 · ₹10000 bought 0.550 units
Nifty 50 17616.30 · ₹10000 bought 0.568 units
Nifty 50 17450.90 · ₹10000 bought 0.573 units
Nifty 50 17398.05 · ₹10000 bought 0.575 units
Nifty 50 18147.65 · ₹10000 bought 0.551 units
Nifty 50 18487.75 · ₹10000 bought 0.541 units
Nifty 50 19322.55 · ₹10000 bought 0.518 units
Nifty 50 19733.55 · ₹10000 bought 0.507 units
Nifty 50 19435.30 · ₹10000 bought 0.515 units
Nifty 50 19528.75 · ₹10000 bought 0.512 units
Nifty 50 18989.15 · ₹10000 bought 0.527 units
Nifty 50 20267.90 · ₹10000 bought 0.493 units
The whole record: across 358 twelve-month periods starting each month from January 1996 to October 2025, all at once ended ahead in 238, about two in three. Vanguard's 2012 study found much the same in the US, the UK and Australia: a lump sum ahead about two-thirds of the time, for a mix of shares and bonds, with twelve monthly instalments and results compared over ten years. The index rose in 258 of the 358 periods, and money waiting to go in earned nothing in our sum.
The choice, then, follows when the money arrives, not which way wins more often. Money that arrives each month is invested as it arrives: a SIP is not a delay, and saving it up to invest once a year would keep it out longer. Money already in hand is the real choice: all at once, or spread over a few months (a systematic transfer plan, STP, moves it in steps from one of the fund house's funds into another) so that no single bad day takes all of it. Spreading did not win more often; it narrowed the range. In the worst of the 358 periods, from 3 December 2007, ₹1.2 lakh put in at once was worth ₹54893 a year later and ₹10000 a month was worth ₹70594. In the period that favoured a lump sum most, from 2 March 2009, a week before that year's lowest close, at once was worth ₹225095 and monthly ₹143495.
What a SIP does not do: it does not stop a fall. In 2008 the monthly buyer still lost ₹34047 of ₹1.2 lakh, and across the record monthly buying ended below the money put in about as often as all at once did: monthly in 99 of the 358 periods, all at once in 100. How much of Maya's money belongs in shares at all is the next lesson's question.
Before any of my money goes in, how do I check a fund?
Reading a Factsheet
Six questions for one page
This factsheet looks like a wall of numbers, stars and badges.
Ask it six questions, and skip the awards and star ratings.
And the returns table tells me what it will do next?
It shows what it did, beside its benchmark. It promises nothing.
A factsheet is the monthly summary a fund house publishes for each fund, a page or two. The full rules sit in the scheme information document (SID) and its short form, the key information memorandum (KIM), which comes with every application form. Six questions cover a factsheet; everything else on it, the awards, star ratings and short-term return badges, a beginner can skip.
Figure 9Factsheet
Reading a factsheet in six zones
Sample Nifty 50 Index FundAn open-ended scheme replicating the Nifty 50 index · factsheet, 30 Sep 2026
★★★★★Award 2026marketing: skipCategoryIndex fund
BenchmarkNifty 50 TRI
Objective
HDFC Bank10.38%
ICICI Bank9.05%
Reliance7.58%
Bharti Airtel5.10%
L&T4.20%
Top ten52.27%
Financial services37.45%
Oil, gas and fuels9.39%
IT7.52%
Cars and auto parts6.65%
Everyday goods (FMCG)5.50%
Expense ratio, direct plan0.20%
Expense ratio, regular plan
Exit loadNil
1 year5 years
Fund, direct plan
Nifty 50 TRI−7.09%6.38%
Tracking difference · tracking error
Fund size · launched
Fund manager, since
Plans · optionsDirect, Regular · Growth, IDCW
Six questions for any fund · pick one
The objective, the category and the benchmark. Here the benchmark is the Nifty 50 TRI, a total return index, which adds back dividends.
What does it do, and what is its yardstick? Read the objective, the category and the benchmark: for a Nifty 50 index fund, "Nifty 50 TRI", a total return index, which adds back dividends. What is inside? The ten largest holdings and the sector weights; Indian funds publish their full portfolio each month within 10 days. In a Nifty 50 index fund the top ten are the index's own, about half the fund.
What does it cost to stay, and to leave? The expense ratio of each plan, direct and regular, and the exit load: "Nil", or say "1% if redeemed within 12 months" (chapter 5). How closely has it kept up? Returns against the benchmark over 1, 3 and 5 years and since launch, for each plan; for an index fund, the tracking difference (the gap itself, published monthly) and the tracking error (how much the gap wobbles; India caps it at 2%). Past returns are shown beside the benchmark and promise nothing.
How risky is it labelled? The of the fund and of its benchmark, side by side wherever performance is shown, on six levels from Low to Very High, set again every month; Nifty 50 index funds and the index itself read Very High. How big, how old, and who runs it? Fund size (assets under management), launch date, the fund manager and since when, the minimum purchase and SIP amount, and the plan and option: Growth keeps payouts inside the fund, while IDCW (income distribution cum capital withdrawal) pays them out of the fund's own assets, which can include investors' own capital, so the NAV drops by the amount paid.
Before any money goes in, turn the page into a checklist you answer yes or no: do I know what it holds, and which index it copies or tries to beat? Have I seen its ten largest holdings and how much of the fund they make up? Do I know the expense ratio of the plan I am buying? Do I know when an exit load would apply? Do I know how it did against its benchmark after costs, or, for an index fund, its tracking difference? Does its riskometer level suit the deadline of the money I would put in?
The sample says Very High risk. What can a fund not protect me from?
What a Fund Cannot Remove
Spreading is not a shield
My fund owns fifty companies. Even if one collapses, the other forty-nine hold it up, right?
Against one company, yes. Even your fund's heaviest is about a tenth. Against the whole market, no.
When would all fifty fall together?
When the whole economy shakes. In 2008 the Nifty 50 fell 59.9% in under ten months, and funds copying it fell with it.
And if I needed my money in the middle of that?
You could sell, at that day's low NAV. In 2020 six debt funds froze withdrawals; the first money came back ten months later.
What spreading does remove: one company's fall moves a fund only by that company's share. Say one member holding 1.33% of the fund, the size of chapter 1's ₹13.30 slice, halved in price (a what-if, not a forecast for any company): the ₹1000 would lose ₹6.65, about 0.67%. Even the fund's heaviest member, 10.16% at that close, halving would take about 5% off the fund, before any other move. Held on its own, the same halving would take half.
What it cannot remove is the market. From its close of 6287.85 on 8 January 2008, the Nifty 50 fell to 2524.20 on 27 October 2008, 59.9% lower, and funds that copied it fell about as far. Nothing promised the way back (the market promises a place to sell, never a price); how long the way back took, then and in other falls, is the next lesson's chart.
Figure 10What no fund removes
Fifty companies, one market
One compartment is half empty. The other forty-nine barely notice: it was ₹13.30 of the ₹1000.
HDFC Bank₹101.55 of the ₹1000
ICICI Bank₹95.57 of the ₹1000
Reliance₹76.08 of the ₹1000
Bharti Airtel₹55.02 of the ₹1000
L&T₹40.82 of the ₹1000
Infosys₹38.97 of the ₹1000
SBI₹37.88 of the ₹1000
Axis Bank₹33.47 of the ₹1000
Kotak Bank₹30.31 of the ₹1000TCSTCS
₹24.70 of the ₹1000
Tata Steel₹13.30 of the ₹1000, the slice of chapter 1, now 50% full
Nor can it remove the wait. Today an Indian fund must normally pay a sale's money within three working days; in 2020 the limit was ten. In April 2020 the trustee of Franklin Templeton's Indian fund house decided to wind up six debt funds, among them a credit-risk fund (one that must keep at least 65% of its money in bonds below the top two grades rating agencies give), because markets "had become illiquid due to the severe impact of COVID-19", in the fund house's words. More than ₹25000 crore of investors' money could not be withdrawn. It came back in fourteen instalments as the bonds were repaid or sold: nothing for ten months; then ₹9121.59 crore in February 2021; about 95% of the April 2020 value by August 2021, sixteen months after the freeze; and the last ₹40.07 crore in May 2025. In all ₹27548.21 crore was paid out, 109.25% of the April 2020 value. The cost was the wait: months with no access to the money, on the funds' timetable rather than the investors'.
Why that was debt funds: a fund that holds the most-traded large companies can usually sell them, and its risk is mostly a falling price. The 2020 freeze came in funds holding company bonds that few would buy that month.
Nor can it remove costs, or you. The expense ratio is charged in bad years too, and no fund stops its owner selling at the bottom. A 2008 seller turned a fall into a permanent loss; a holder who did not need the money did not have to sell.
The money's deadline decides where it belongs: money needed soon does not belong where a 60% fall or a frozen exit could meet it. How to split Maya's money by deadline is the next lesson.
How do I split my money when my restaurant already carries so much of my risk?
Before you go
Check yourself
4 questions from this lesson. Pick an answer to see why, then slide on to the next.
Question 1 of 4
Questions readers ask
Common questions
What is the difference between a mutual fund, an index fund and an ETF?
A mutual fund pools many investors' money and invests it by a stated plan. An index fund is a mutual fund that copies an index such as the Nifty 50 instead of picking shares. An ETF usually copies an index too, but its units trade on a stock exchange at market prices, so you buy them through a broker into a demat account; fund units are bought from the fund house at the day's NAV.
Is a fund with a lower NAV cheaper?
No. NAV is the value of one unit. ₹10000 buys ten times as many units of a ₹10 fund as of a ₹100 fund, and if both hold the same investments and rise 10%, both are worth the same. A low NAV often just means a young fund, or one that has fallen.
Is a SIP better than a lump sum?
Neither wins every time. On the Nifty 50's history since 1996, a year's money put in at once ended ahead of twelve monthly instalments in about two of every three 12-month periods; in falling years such as 2008, monthly buying lost far less. A SIP fits money that arrives monthly; a lump sum is money you already have.
Can a mutual fund lose money?
Yes. A fund falls when what it holds falls: funds copying the Nifty 50 fell about 60% between January and October 2008. A fund can also stop withdrawals: six Franklin Templeton debt funds in India did so in April 2020, paid nothing for ten months, and returned about 95% of their April 2020 value within sixteen months, the rest in later instalments.
What is an expense ratio, and how is it charged?
The fund's yearly cost as a share of your money, taken from the fund a little every day, so it appears as a lower NAV rather than a bill. In India, from 1 April 2026, an index fund's or ETF's base cost may not exceed 0.90% a year; each factsheet shows the actual figure for each plan.
What is the difference between a direct and a regular plan?
The same fund and holdings. A regular plan is bought through a distributor and pays them a commission out of its expenses, so its NAV grows a little more slowly; a direct plan, offered in India since 1 January 2013, is bought without a distributor and pays no commission. ETFs, bought on the exchange, have no such pair.
Words to keep
The 12 words this lesson used, in plain English
Mutual fund
A pool of many people's money invested by a written plan; each investor owns units, equal slices of the whole.